

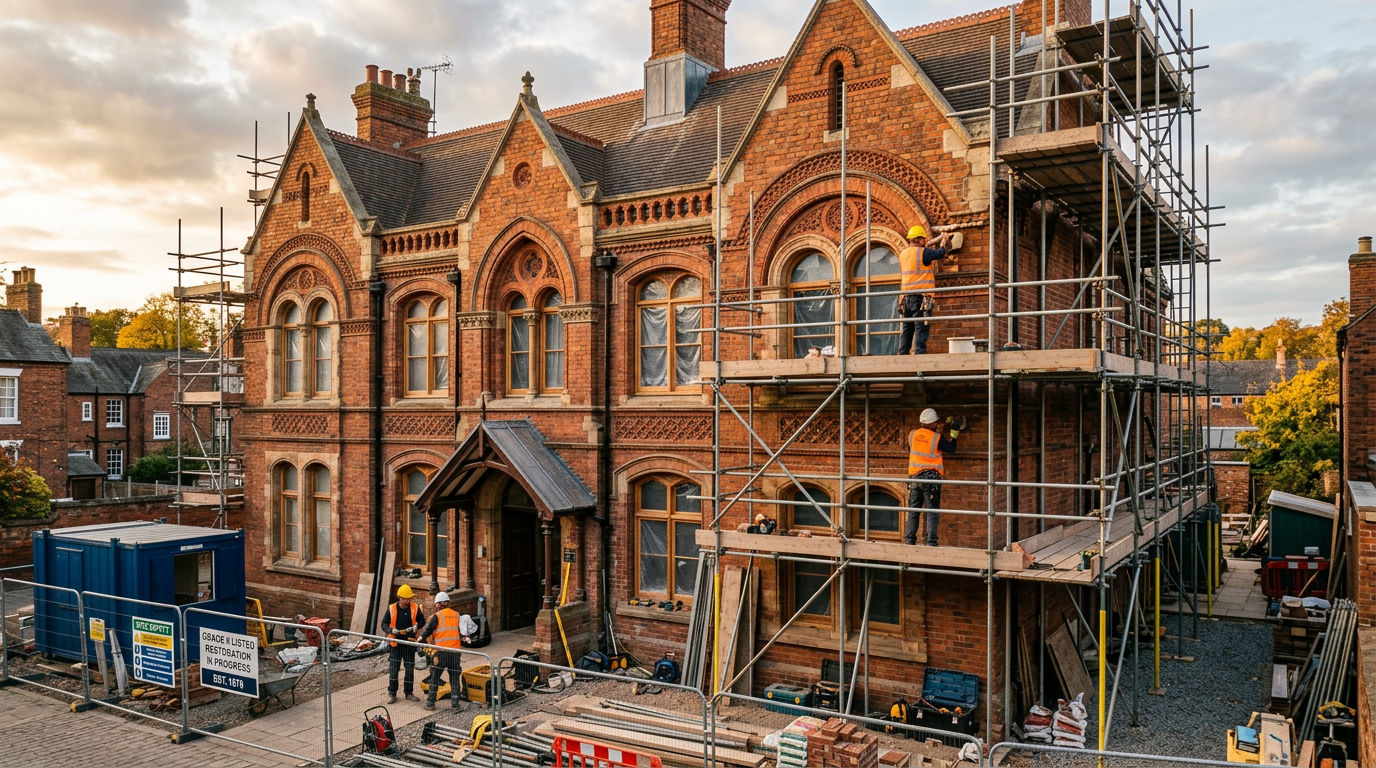
Understanding Listed Building Refurbishment Bridging Loans
A refurbishment bridging loan is a short-term financing solution specifically designed to facilitate renovations and improvements on properties, particularly those classified as Grade II listed buildings. These loans are essential for property owners looking to restore or enhance the historical and architectural integrity of their homes while ensuring compliance with strict regulations that govern listed properties.
Grade II listed buildings are recognized for their special architectural or historic interest. They represent a significant part of the UK’s cultural heritage, making their preservation vital. However, refurbishing these properties can be complex due to the need for adherence to conservation guidelines. This is where refurbishment bridging loans come into play. They provide the necessary funds quickly, allowing homeowners to initiate refurbishment projects without delay, which is crucial given the often time-sensitive nature of such works.
These loans are typically secured against the property itself and can cover a variety of refurbishment costs, including structural repairs, aesthetic upgrades, and energy efficiency improvements. The importance of refurbishment bridging loans for Grade II listed buildings cannot be overstated; they not only help maintain the unique character of these properties but also contribute to the overall enhancement of local communities and heritage sites.
Why Choose a Bridging Loan for Heritage Refurbishment?
When it comes to financing heritage refurbishment projects, bridging loans offer several advantages over traditional financing options. One of the most significant benefits is the speed of funding. Traditional loans can take weeks or even months to process, while bridging loans can often be approved and disbursed within a matter of days. This rapid access to funds is particularly beneficial for property owners who may face tight deadlines for refurbishment projects or who need to act quickly to secure a property before it falls into disrepair.
Another advantage is the flexibility in terms. Bridging loans can be tailored to meet the specific needs of the borrower, including the loan amount, repayment terms, and interest rates. This flexibility allows property owners to structure their financing in a way that aligns with their refurbishment plans and cash flow. For example, if a property owner anticipates a quick sale or refinancing after the refurbishment, they can select a short-term loan with a higher interest rate that will be paid off quickly.
In comparison to traditional loans, bridging loans also have less stringent eligibility criteria. While conventional lenders often require extensive documentation and a lengthy approval process, bridging lenders typically focus on the property’s value and the borrower’s refurbishment plans. This makes it easier for owners of Grade II listed buildings to secure funding, even if they have less-than-perfect credit histories or unconventional financial situations.
Moreover, bridging loans can be used for various types of refurbishment projects, from minor cosmetic updates to extensive structural renovations. This versatility makes them an ideal choice for property owners looking to enhance the value and appeal of their listed buildings without the constraints often associated with traditional financing options.
Key Considerations for Grade II Listed Renovations
When embarking on a Grade II listed renovation, there are several critical considerations that property owners must keep in mind. First and foremost is the need for planning permissions and adherence to regulations. The UK government has strict guidelines regarding alterations to listed buildings, aimed at preserving their historical significance. Before any work begins, it is essential to consult with local planning authorities to determine what changes are permissible.
Additionally, the impact on property value is a crucial factor. While renovations can increase the market value of a property, it is vital to ensure that the changes made are in keeping with the building’s character. Over-improvement or inappropriate alterations can lead to a decrease in value, as potential buyers may be deterred by a lack of authenticity or historical integrity.
Another important distinction is between restoration and renovation. Restoration aims to return a building to its original state, which often involves extensive research and careful craftsmanship. In contrast, renovation may involve modernizing aspects of the property while maintaining its historical features. Understanding the difference between these approaches is essential for property owners to align their refurbishment plans with their goals and the requirements of listed building regulations.
The Application Process for Listed Building Refurbishment Bridging Loans
The application process for securing a refurbishment bridging loan can be straightforward if approached methodically. Here’s a step-by-step guide to help navigate the process:
- Assess Your Needs: Determine the scope of your refurbishment project and the amount of funding required.
- Research Lenders: Look for lenders who specialize in bridging loans for listed buildings. Compare their terms, interest rates, and reputation.
- Prepare Documentation: Gather necessary documents, including proof of ownership, refurbishment plans, and any relevant planning permissions.
- Submit Your Application: Complete the application form provided by the lender, ensuring all information is accurate and comprehensive.
- Property Valuation: The lender will conduct a valuation of the property to assess its worth and the feasibility of the proposed refurbishment.
- Loan Approval: If approved, review the loan agreement carefully, paying attention to the terms and conditions before signing.
- Receive Funds: Once the agreement is finalized, the funds will be released, allowing you to commence your refurbishment project.
Throughout this process, it is crucial to avoid common pitfalls, such as failing to provide complete documentation or underestimating the costs involved in the refurbishment. Engaging with professionals, such as architects or surveyors familiar with listed buildings, can also help streamline the application process and ensure compliance with all regulations.
Case Studies: Successful Grade II Listed Renovations
Examining successful case studies of Grade II listed renovations can provide valuable insights into the challenges and solutions encountered during these projects. One notable example is the refurbishment of a Victorian terrace in London, which faced significant structural issues and required extensive restoration work to preserve its original features.
The property owner secured a refurbishment bridging loan to fund the project, which included repairing the façade, restoring original windows, and upgrading the interior to modern standards while maintaining historical accuracy. The challenges included sourcing period-appropriate materials and navigating the complexities of local planning regulations. However, by working closely with conservation experts and local authorities, the owner successfully completed the renovation.
The impact of this project on the community was profound. Not only did it enhance the aesthetic appeal of the street, but it also increased property values in the area and attracted new residents interested in preserving the local heritage.
Another example is a rural farmhouse that underwent a comprehensive renovation to convert it into a family home while retaining its historical charm. The owner utilized a refurbishment bridging loan to cover costs associated with structural repairs, modern amenities, and energy efficiency upgrades. The project faced challenges such as integrating modern heating systems without compromising the building’s integrity. By employing skilled craftsmen and adhering to conservation guidelines, the renovation was completed successfully, resulting in a home that honored its heritage while providing modern comforts.
These case studies illustrate the potential of refurbishment bridging loans to facilitate successful Grade II listed renovations, highlighting the importance of careful planning, expert guidance, and community engagement in preserving the UK’s architectural heritage.
Finding the Right Lender for Your Heritage Refurbishment
Choosing the right lender for a refurbishment bridging loan is crucial for the success of your project. Here are key factors to consider when evaluating potential lenders:
- Specialization: Look for lenders who specialize in bridging loans for listed buildings or heritage properties. Their expertise will ensure they understand the unique challenges associated with these types of projects.
- Loan Terms: Compare the terms offered by different lenders, including interest rates, repayment periods, and any fees associated with the loan. Ensure that the terms align with your financial situation and project timeline.
- Customer Reviews: Research customer reviews and testimonials to gauge the lender’s reputation and customer service. A lender with positive feedback is more likely to provide a smooth and supportive borrowing experience.
- Flexibility: Assess the lender’s willingness to accommodate your specific needs, such as customized repayment plans or the ability to extend the loan if necessary.
When meeting with potential lenders, prepare a list of questions to ensure you have a clear understanding of their offerings. Inquire about their experience with listed properties, the application process, and any potential challenges you may face during your refurbishment project. A knowledgeable lender will provide valuable insights and guidance, helping you make informed decisions throughout the financing process.
Cost Implications of Refurbishing Listed Properties
Budgeting for the refurbishment of a Grade II listed property requires careful planning and consideration of various cost implications. The initial budget should account for both expected and unexpected expenses. Common costs associated with refurbishment projects include:
- Structural Repairs: Essential repairs to maintain the building’s integrity can be costly, especially if extensive work is needed.
- Specialist Materials: Sourcing period-appropriate materials may require additional funds, as these can be more expensive than standard options.
- Labor Costs: Hiring skilled craftsmen familiar with historical restoration techniques is crucial, and their services may come at a premium.
- Planning Fees: Engaging with local authorities for planning permissions and inspections can incur fees that should be factored into the budget.
Unexpected costs can arise during the refurbishment process, often due to hidden issues that become apparent once work begins. For example, structural problems may require additional repairs, or outdated electrical systems may need upgrading to meet modern safety standards. It is advisable to set aside a contingency fund, typically around 10-20% of the total budget, to cover these unforeseen expenses.
Beyond refurbishment bridging loans, other financing options may be available to support your project. These include grants for heritage conservation, traditional mortgages, or personal loans. Exploring all available options can help you secure the necessary funds while ensuring your refurbishment project remains within budget.
Future Trends in Listed Property Improvement in the UK
The landscape of listed property improvement in the UK is evolving, with several future trends shaping the way these projects are approached. One significant trend is the increasing focus on sustainability in renovations. Property owners are becoming more aware of the environmental impact of their renovations and are seeking ways to incorporate sustainable practices, such as using eco-friendly materials and energy-efficient systems.
Technological advancements are also playing a crucial role in the refurbishment of listed buildings. Innovations such as Building Information Modelling (BIM) and advanced energy modeling tools allow property owners and contractors to plan and execute renovations more effectively, ensuring that the historical integrity of the building is preserved while enhancing its functionality.
Furthermore, government initiatives supporting heritage projects are gaining momentum. Various funding programs and incentives are being introduced to encourage property owners to invest in the restoration and improvement of listed buildings. These initiatives not only promote the preservation of cultural heritage but also contribute to local economies by attracting tourism and fostering community engagement.
As these trends continue to develop, property owners embarking on refurbishment projects for Grade II listed buildings can expect to benefit from a more supportive environment that prioritizes sustainability, innovation, and heritage conservation.
Frequently Asked Questions
What is a listed building refurbishment bridging loan?
A listed building refurbishment bridging loan is a short-term loan for refurbishing Grade II listed buildings, providing quick access to funds for necessary renovations.
How quickly can I get a bridging loan for a listed property?
Typically, you can receive a bridging loan within a few weeks, depending on the lender and the complexity of your application.
What are the eligibility criteria for these loans?
The property must be Grade II listed, and you need a clear refurbishment plan that adheres to local regulations and conservation guidelines.
Can I use a bridging loan for both renovation and restoration?
Yes, bridging loans can be used for both types of projects, allowing flexibility in how you approach your refurbishment.
What are the risks associated with refurbishment bridging loans?
Risks include higher interest rates compared to traditional loans, potential for delays in project completion, and fluctuations in property value that may affect your investment.
