
Can You Get a UK Mortgage While Living Abroad?
Yes, it can be possible to obtain a mortgage on UK property while you live overseas. The route depends on where you live, how and where your income is earned, your deposit, the property, its intended use and the evidence available to support the application.
This guide explains the application from an informational perspective. If you already have a UK property purchase or refinance in mind, see Lockwell Finance’s Overseas Resident Mortgages service for the commercial mortgage route.
Can You Get a UK Mortgage While Living Overseas?
In many cases, yes. Living outside the United Kingdom does not automatically prevent you from obtaining a mortgage on UK property.
The important question is whether your residence, income, deposit, banking history, proposed property and ownership structure meet the criteria of a lender that considers overseas-resident applications.
An overseas-resident mortgage is not one single product with one set of rules. A British expat purchasing a UK rental property, an overseas resident buying a future home and an international investor refinancing property already owned in the UK may all need different lender routes.
This is why an application should start with the complete borrower and property profile rather than an advertised mortgage rate alone.
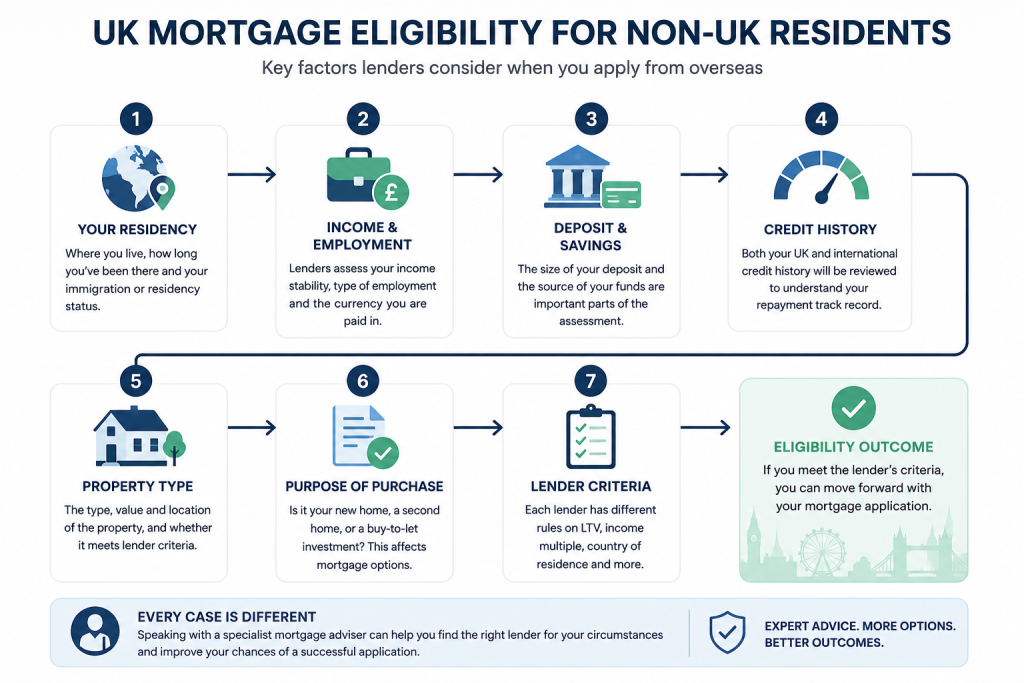
What “Non-UK Resident” Means for a Mortgage Application
For this guide, the important issue is where you currently live. You may be a British citizen living abroad or a non-British citizen living outside the UK. In both cases, overseas residence can affect how a lender assesses income, banking, credit history, source of funds and documentation.
Overseas resident
Someone who currently lives outside the UK. The person may be a British citizen or a foreign national.
Foreign national
Someone who does not hold British citizenship. They may live in the UK or overseas.
Keeping those definitions separate matters. If your main issue is that you live abroad, the overseas-resident route is the natural starting point. If you live in the UK but your citizenship, visa or residency position is the main concern, see the Foreign National Mortgages service instead.
What Lenders Assess When You Apply from Abroad
There is no universal overseas-resident lending policy. Different lenders can place different weight on the borrower, the income, the property and the proposed transaction.
Where you live can affect which lenders are able or willing to consider the application and what additional checks may be required.
Lenders may review whether you are employed, self-employed or a business owner, where the income originates and how consistently it can be evidenced.
The currency in which you are paid can influence affordability calculations and lender choice.
The lender and legal professionals may need a clear evidence trail showing the amount available and where the funds came from.
UK credit information can be relevant where available, but overseas banking and financial evidence may become particularly important when your UK credit footprint is limited.
Price, location, type, tenure, condition and whether the property will be occupied or rented can all affect the mortgage route.
Personal ownership, joint ownership, a UK SPV or another company structure can create different lender and document requirements.
Residential or Buy-to-Let: Property Use Changes the Assessment
One of the first questions is what the UK property is actually for. A mortgage for a property you intend to occupy is assessed differently from finance for a rental investment.

Residential property
Where you or your family will occupy the property, personal affordability, income, commitments, deposit and residency circumstances can be central to the assessment.
Buy-to-Let property
For a property that will be rented to tenants, lenders commonly consider the expected rent, property, loan-to-value, deposit, borrower profile and proposed ownership structure.
If the main objective is UK rental-property finance rather than overseas-resident guidance generally, see Lockwell Finance’s Buy-to-Let Mortgages page.
Documents to Prepare Before You Approach a Lender
Overseas applications can involve more evidence than a straightforward UK-resident case. Preparing the core documents early makes it easier to identify gaps before underwriting begins.

Depending on your circumstances and lender, useful information can include:
- Passport or accepted identification.
- Evidence of your current overseas address.
- Employment, business or self-employment information.
- Payslips, accounts, tax documents or other relevant income evidence.
- Recent personal or business bank statements where applicable.
- Deposit amount and source-of-funds evidence.
- Details of existing loans or mortgages.
- Information about the UK property and purchase price or current value.
- Expected rent where the property will be let.
- Details of the proposed personal, joint or company ownership structure.
The exact evidence varies between lenders. Documents issued outside the UK may also be subject to additional lender, legal or translation requirements.
How to Apply for a UK Mortgage from Abroad
A well-structured overseas application usually starts by clarifying the borrower and property before selecting the mortgage route.

Define the borrower profile
Establish where you live, your citizenship where relevant, how your income is earned and whether you are applying personally, jointly or through a company.
Clarify the UK property and intended use
Confirm whether the transaction is a purchase or refinance and whether the property will be occupied, rented or held as an investment.
Review income, deposit and evidence
Check the income source and currency, available deposit or equity, banking evidence and source of funds.
Identify realistic lender routes
Compare the complete circumstances with lenders that consider the relevant country of residence, income structure, property and ownership arrangement.
Submit the application and supporting evidence
The lender reviews the case and may request further information during underwriting.
Valuation, mortgage offer and legal work
The property valuation, lender conditions and conveyancing or refinance work then progress towards completion.
Deposits, Rates and Costs: Why There Is No Single Overseas-Resident Figure
It is tempting to look for one minimum deposit, income threshold or mortgage rate for every applicant living overseas. In practice, those figures can change with the lender and the complete case.
Deposit requirements can be affected by your country of residence, property use, borrower structure, credit profile, income, currency, property and requested loan-to-value. The rate available can also change according to those factors and the mortgage product selected.
When comparing borrowing, consider more than the headline interest rate. Product fees, broker fees, valuation costs, legal work, surveys and costs connected with transferring or evidencing funds from overseas can all affect the wider transaction.
Tax treatment can also vary according to the transaction and your circumstances. Obtain appropriate legal or tax advice before committing to a purchase where you are unsure how UK property taxes apply to you.
Common Reasons Overseas Mortgage Applications Are Delayed
Many delays are not caused by the fact that the applicant lives overseas itself. They arise because important information cannot be verified quickly or the case was sent to a lender whose criteria do not fit the circumstances.
- Incomplete income evidence.
- Bank statements that do not clearly connect to declared income.
- An unclear source of deposit or purchase funds.
- Income in a currency that does not fit the selected lender’s criteria.
- Limited UK credit or address history without sufficient alternative evidence.
- Property characteristics outside the lender’s acceptable criteria.
- Missing company or ownership information.
- Overseas documents that require further verification or translation.
- Applying before checking whether the lender considers the applicant’s country of residence.
Preparing the case around the borrower, property and evidence before submission can reduce avoidable back-and-forth during underwriting.
Practical Checklist Before You Apply
Before approaching a lender or mortgage adviser, make sure you can answer the main questions that determine the route.
- Where do you currently live?
- What is your income source and currency?
- Is the UK property residential or Buy-to-Let?
- What is the purchase price or current property value?
- How much deposit or equity is available?
- Can you evidence the source of the funds?
- What existing debts or mortgages do you have?
- Will you buy personally, jointly or through a company?
- Do you have recent income and banking documents ready?
- Is there an important purchase or refinance deadline?
Already Have a UK Property Purchase or Refinance in Mind?
This article covers the general questions involved in obtaining a UK mortgage while living overseas. For a real transaction, start with the commercial overseas-resident mortgage service, where the residence, income, deposit, property, ownership structure and required timeline can be reviewed together.
Explore Overseas Resident MortgagesQuestions About Getting a UK Mortgage While Living Abroad
Can I get a UK mortgage if I do not live in the UK?
Potentially. Living overseas does not automatically prevent you from obtaining a mortgage on UK property. Availability depends on your country of residence, income, deposit, property, intended use, ownership structure and the lender’s criteria.
Can I use overseas income for a UK mortgage?
Some lenders consider income earned outside the UK. The source, currency, consistency and supporting evidence can all affect how it is assessed.
Do I need a UK credit history?
Not in every case. A limited UK credit footprint can narrow the available routes, but lenders considering overseas residents may also look at banking, address, income and other financial evidence.
Do overseas residents always need a larger deposit?
There is no single deposit percentage that applies to every overseas-resident application. Requirements can vary with the lender, property, borrower profile, mortgage purpose, income, residence and requested loan-to-value.
Can I get a UK Buy-to-Let mortgage while living overseas?
It may be possible. Lenders can consider the expected rent, property, deposit, country of residence, borrower profile and intended ownership structure when assessing an overseas Buy-to-Let application.
Is an overseas resident the same as a foreign national?
No. Overseas resident describes where you live. Foreign national describes citizenship. A British citizen living abroad is therefore an overseas resident but not a foreign national, while a non-British citizen living in the UK may be a foreign national without being an overseas resident.
Can I apply through a company or SPV?
Some mortgage routes may consider company ownership, particularly in property investment. The company jurisdiction, directors, shareholders, property, income or rent, deposit and guarantees can all affect the lender’s assessment.
What should I prepare before discussing an overseas-resident mortgage?
Start with your country of residence, income source and currency, deposit or equity, source of funds, UK property details, required mortgage amount, ownership structure and intended completion timeline.
The Key Point
Getting a UK mortgage while living abroad is not determined by residence alone. The lender needs to understand the complete borrower and property profile: where you live, how you earn, the currency involved, your deposit, banking evidence, intended property use and ownership structure.
Prepare those details early, distinguish overseas-residence questions from citizenship or visa questions, and check the lender route before submitting an application.
If you are ready to discuss an actual UK purchase or refinance, continue to the Overseas Resident Mortgages service page.
Mortgage and finance availability is subject to status, affordability, valuation, lender criteria and underwriting. Your home or property may be repossessed if you do not keep up repayments on your mortgage or another debt secured against it. This article provides general information and does not constitute legal, tax or financial advice.