

Buying a second home, holiday property or buy-to-let can involve a substantially larger Stamp Duty Land Tax bill than buying your only home.
In England and Northern Ireland, buying an additional residential property will usually mean paying SDLT rates that are five percentage points higher than the standard residential rates. Whether those higher rates apply depends on what property you already own, what you will own at completion and whether you are replacing your main residence.
This guide explains the current second-home stamp duty rates, how to calculate the tax, when the surcharge may not apply, when you can claim a refund and what landlords and investors should budget for before completing a purchase.
Important: SDLT applies in England and Northern Ireland. Scotland uses Land and Buildings Transaction Tax (LBTT), while Wales uses Land Transaction Tax (LTT).

In This Guide
- How much stamp duty you pay on a second home
- Current second-home SDLT rates
- Worked examples
- When the higher rates apply
- Second-time buyers versus second-home buyers
- When the higher rates may not apply
- Claiming back second-home stamp duty
- Buy-to-let and holiday-home purchases
- Limited-company purchases
- Non-UK resident buyers
- How and when SDLT is paid
- What to check before completion
- Frequently asked questions
How Much Stamp Duty Do You Pay on a Second Home?
If buying a residential property in England or Northern Ireland means that you will own more than one qualifying residential property, you will usually pay the higher SDLT rates for additional properties.
From 1 April 2025, the higher rates are:
| Property price band | SDLT rate for additional properties |
|---|---|
| Up to £125,000 | 5% |
| £125,001 to £250,000 | 7% |
| £250,001 to £925,000 | 10% |
| £925,001 to £1.5 million | 15% |
| Above £1.5 million | 17% |
These rates are progressive. You do not pay one percentage across the entire purchase price. Each portion of the property price is charged at the rate for its band.
You can also use the Lockwell Finance stamp duty calculator to estimate the tax alongside your wider property-purchase budget.
Second Home Stamp Duty Examples
The following examples use the higher residential rates applying in England and Northern Ireland from 1 April 2025.
| Purchase price | Calculation | Total SDLT |
|---|---|---|
| £250,000 | 5% on £125,000 + 7% on £125,000 | £15,000 |
| £300,000 | 5% on £125,000 + 7% on £125,000 + 10% on £50,000 | £20,000 |
| £500,000 | 5% on £125,000 + 7% on £125,000 + 10% on £250,000 | £40,000 |
| £600,000 | 5% on £125,000 + 7% on £125,000 + 10% on £350,000 | £50,000 |
For example, on a £300,000 additional residential property:
- 5% of the first £125,000 = £6,250
- 7% of the next £125,000 = £8,750
- 10% of the remaining £50,000 = £5,000
Total SDLT: £20,000
HMRC uses the same £300,000 example in its current guidance on higher rates for additional residential properties.
The exact tax position can change if the property is mixed-use, is purchased through a company, qualifies for a relief, is bought by a non-UK resident or is replacing a main residence.

What Is the Second Home Stamp Duty Surcharge?
The phrase “second home surcharge” is commonly used to describe the higher SDLT rates charged on additional residential property.
It is not a separate fixed fee added after calculating normal stamp duty. Instead, the SDLT percentages applying to each residential price band are five percentage points higher.
For example, the normal residential rate for the portion between £250,001 and £925,000 is 5%. The corresponding additional-property rate is 10%.
The higher rates can apply to:
- second homes
- holiday homes
- buy-to-let properties
- another home bought before an existing home has been sold
- jointly purchased property where one buyer already owns another qualifying residential property
- property purchases involving ownership of residential property overseas
The crucial question is usually what residential property each buyer will own at the end of the day on which the new purchase completes.
When Does Second Home Stamp Duty Apply?
HMRC’s higher-rate rules generally apply where you purchase a residential property or interest worth £40,000 or more and, after the transaction, it will not be the only residential property worth £40,000 or more that you own or part-own.
Property owned anywhere in the world may need to be considered, not only property in the UK.
This means a buyer who owns an apartment abroad and then purchases a home in England could potentially fall within the additional-property rules even if the English property is their first UK purchase.
Buying Jointly
For joint purchases, the circumstances of each purchaser matter.
If one buyer already owns another qualifying residential property, the higher rates can potentially apply to the entire new purchase even if the other buyer owns no property.
Married couples and civil partners are also subject to specific rules, so ownership should be checked before contracts are exchanged rather than assumed from whose name appears on an existing mortgage.
Second-Time Buyer Stamp Duty Is Not the Same as Second-Home Stamp Duty
A second-time buyer is simply someone who has owned a property before. That does not automatically mean the additional-property surcharge applies.
Consider three common situations.
You Sell Your Current Main Home Before Buying the Next One
If your previous main residence has been sold and the new property replaces it as your main residence, the higher rates will usually not apply.
You would normally be assessed under the standard residential SDLT rates.
You Keep Your Current Home and Buy Another
If you retain your existing home and purchase another residential property, you will generally own more than one qualifying property at completion.
The additional-property rates may therefore apply.
You Buy the New Main Home Before Selling the Old One
If your old main residence has not been sold by the date you complete on your new one, you may initially have to pay the higher rates because you temporarily own two properties.
However, you may later qualify for a refund if you dispose of your previous main residence within the required period.

When Might the Higher Stamp Duty Rates Not Apply?
Owning more than one property does not automatically mean every future transaction is taxed at the additional-property rates.
HMRC identifies several situations in which property or transactions can fall outside the higher-rate rules.
Replacing Your Main Residence
If you are replacing your main residence and your previous main residence has already been sold, you may qualify for the standard residential rates rather than the additional-property rates.
HMRC’s rules also allow for situations where the previous main residence was disposed of within the relevant 36-month period.
Property Worth Less Than £40,000
A residential property or interest worth less than £40,000 is generally excluded when applying the higher-rate test.
This does not mean every transaction below £40,000 is automatically outside every possible SDLT rule, but it is an important threshold for the additional-property rules.
Mixed-Use Property
A transaction involving both residential and non-residential property can be treated differently.
A common example is a shop with a flat above it.
Property classification can be highly fact-specific, so do not assume a property qualifies as mixed-use simply because part of it has some commercial characteristic.
Caravans, Mobile Homes and Houseboats
Certain moveable properties, including caravans, mobile homes and houseboats, can fall outside the additional residential-property rules unless they have become permanent fixtures.
Certain Transfers Between Spouses or Civil Partners
The higher rates do not apply to certain transfers of ownership between spouses where nobody else is involved in the transfer.
That does not necessarily mean no SDLT of any kind is due, because the wider tax treatment can depend on whether consideration is being given or debt is being transferred.
Increasing Your Interest in Your Main Residence
Specific rules can prevent the higher rates applying when you increase your ownership interest in a property that is already your only or main home, provided HMRC’s conditions are met.
Because these exceptions are technical, complex ownership arrangements should be checked with your conveyancer or a suitably qualified property-tax adviser before exchange.
Is There a Stamp Duty Second Home Loophole?
It is better to think about statutory rules, exemptions and reliefs than “stamp duty loopholes”.
If SDLT is legally due, simply changing the description of a transaction does not remove the liability. However, the higher additional-property rates genuinely do not apply in every situation.
Potentially relevant circumstances include:
- replacing your main residence
- buying a property below the relevant £40,000 additional-property threshold
- a genuine mixed-use transaction
- certain spouse or civil-partner transfers
- qualifying increases in ownership of your existing main home
- transactions involving property that is not treated as a dwelling for these rules
The correct treatment depends on the actual facts of the purchase.
For a broader explanation of legitimate reliefs and lower-rate situations, read our guide to reducing stamp duty legally in the UK.
Can You Claim Back Second Home Stamp Duty?
Yes, in some circumstances.
A common example occurs when you purchase your new main residence before selling your previous main residence. Because you own two properties at completion, you may have to pay the higher SDLT rates initially.
If you then sell or give away your previous main home within three years of purchasing the new home, you may be able to apply to HMRC for a refund of the higher-rate element.
A refund will generally not be available if:
- you or your spouse still own part of the previous main home
- the additional-property rates continue to apply for another reason
For previous homes sold on or after 29 October 2018, HMRC normally requires the refund application within 12 months of whichever is later:
- the sale of the previous main residence, or
- the filing date of the SDLT return for the new residence
Exceptional-circumstances provisions can apply in limited situations where the former main home could not be sold within three years.
For a detailed explanation of the claim routes, information required and common refund scenarios, see our Stamp Duty Refund UK guide.
Stamp Duty on Buy-to-Let Property
A buy-to-let property will commonly be an additional property where the purchaser already owns their home or another rental property.
In that situation, the higher residential SDLT rates normally apply.
For landlords, stamp duty should therefore be treated as part of the cash required for the acquisition rather than as an afterthought.
A purchase budget may need to include:
- deposit
- SDLT
- legal costs
- valuation costs
- mortgage fees
- survey costs
- refurbishment or maintenance expenditure
- insurance
- initial letting costs
- a contingency for unexpected expenses
For example, an investor purchasing a £300,000 additional rental property would need to account for the £20,000 SDLT example above in addition to the deposit and other transaction costs.
If you are considering finance for a rental purchase, Lockwell’s buy-to-let mortgage service explains the information lenders typically consider, including the deposit, rent, borrower profile and proposed ownership structure.
What About Holiday Homes?
A holiday home can also be treated as an additional residential property.
It does not need to produce rental income for the higher-rate rules to apply. A residential property bought mainly for personal holidays can still trigger the additional-property rates if you already own another qualifying residential property.
If the property is intended to operate as a commercial holiday let, mortgage criteria and the tax position are separate considerations. The fact that specialist holiday-let finance may be available does not by itself change the SDLT classification.
Buying a Second Property Through a Limited Company
Purchasing through a limited company or SPV does not provide a general exemption from higher SDLT rates.
HMRC states that companies generally pay the higher rates when buying residential property for £40,000 or more, subject to the detailed rules. Separate rules can apply to certain high-value residential purchases by corporate bodies.
The ownership structure can also affect:
- mortgage availability
- lender criteria
- personal guarantees
- accounting
- corporation tax
- future extraction of profits
- Capital Gains Tax considerations on transfers
- SDLT when property is moved between personal and company ownership
A company structure should therefore be considered as part of the wider investment strategy rather than selected solely because of stamp duty.
Lockwell supports limited-company and SPV buy-to-let applications, but the mortgage structure itself is not tax advice. Obtain appropriate tax and legal advice before deciding how a property should be purchased.
Do Overseas Properties Count?
They can.
When determining whether you own another residential property for the higher-rate rules, HMRC can take qualifying residential property held anywhere in the world into account.
For example, someone who owns a home outside the UK and purchases a residential property in England may potentially face the higher additional-property rates.
This is particularly important for:
- British expats
- foreign nationals buying UK property
- overseas landlords
- people who have inherited property abroad
- buyers who jointly own a family property overseas
Do not assume that an overseas property can be ignored simply because it is outside the UK.
Do Non-UK Residents Pay More Stamp Duty?
Potentially.
A separate 2% SDLT surcharge can apply to non-UK resident purchasers of residential property in England and Northern Ireland.
Where applicable, this can be charged on top of other SDLT rates, including the higher rates for additional dwellings.
This means a non-UK resident buying an additional property can face a different calculation from a UK-resident buyer purchasing the same property.
SDLT has its own residence rules, which are not necessarily identical to the residence tests used for other UK taxes.
If you live overseas and are also considering how to fund the purchase, Lockwell’s UK mortgage support for overseas residents and international buyers covers the mortgage side of the transaction.
How Do You Pay Stamp Duty on a Second Home?
The basic process is the same as for other SDLT transactions.
1. Establish the SDLT Position
Confirm:
- the purchase price
- whether the property is residential or mixed-use
- what other property each purchaser owns
- whether the new property replaces a main residence
- whether the higher rates apply
- whether the non-UK resident surcharge applies
- whether a relief or exemption may be available
2. Calculate the Amount Due
Apply the relevant rates progressively to the purchase price.
For straightforward residential transactions, HMRC’s calculator or the Lockwell Finance stamp duty calculator can provide a useful initial estimate.
Complex transactions should be checked professionally.
3. Submit the SDLT Return
An SDLT return normally needs to be submitted to HMRC within 14 days of completion.
A solicitor, conveyancer or agent will usually submit the return on the buyer’s behalf, although the buyer remains responsible for ensuring the obligations are met.
4. Pay the Tax
The SDLT payment is also normally due within 14 days of completion.
Where a conveyancer handles the transaction, the SDLT amount is commonly collected as part of the completion monies and then paid to HMRC.
5. Keep Your Records
Keep copies of:
- the SDLT return
- completion statement
- payment confirmation
- purchase documents
- evidence relating to any claimed relief
- documents relating to the disposal of a previous main residence if a later refund may be claimed
These records can be particularly important if you subsequently need to amend the return or request a refund.
What to Check Before Buying a Second Property
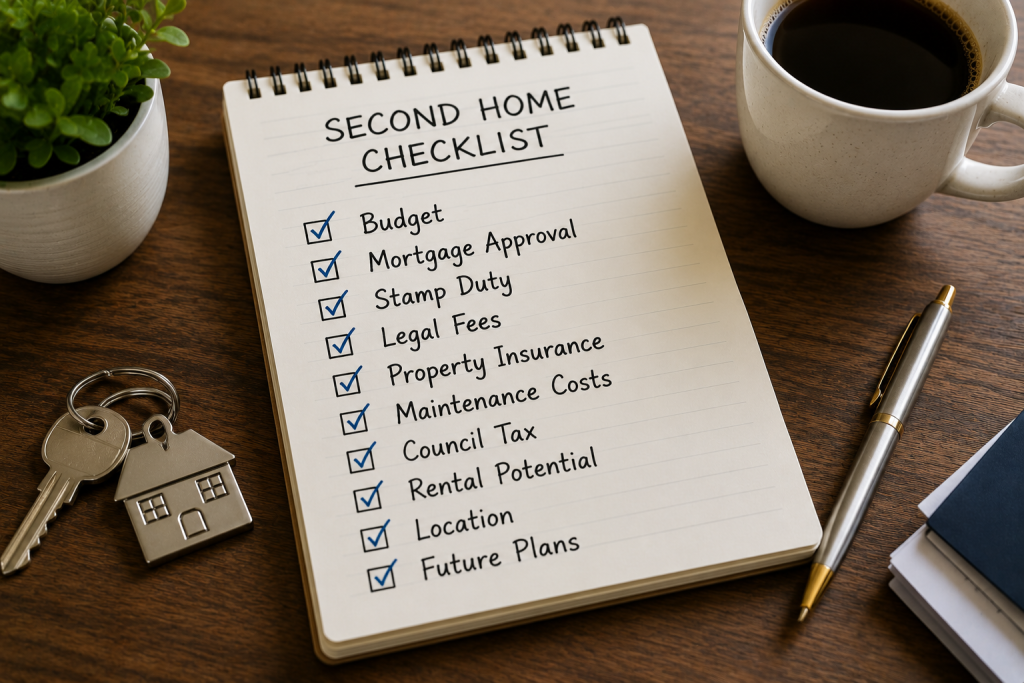
Before you exchange contracts, work through the following checklist:
- Will you own another residential property at completion?
- Do you or another purchaser own property overseas?
- Is any property jointly owned or part-owned?
- Is the new purchase in England, Northern Ireland, Scotland or Wales?
- Is it fully residential or genuinely mixed-use?
- Is the purchase price or property interest worth £40,000 or more?
- Are you replacing your main residence?
- Has your previous main residence already been sold?
- Are you buying jointly with someone who already owns property?
- Are you buying personally or through a company?
- Could the non-UK resident surcharge apply?
- Might you later qualify for a higher-rate refund?
- Have you included SDLT in the cash required for completion?
- Have you budgeted for legal, valuation, mortgage and other property-purchase costs?
Completing these checks early is especially important if your deposit or cash reserves are tight. A stamp-duty bill that was not included in the original budget can create a significant funding gap immediately before completion.
Common Second-Home Stamp Duty Mistakes
Assuming Every Second-Time Buyer Pays the Surcharge
Having owned a property before is not the test. Replacing a main residence can produce a different result from retaining one property and buying another.
Forgetting About Overseas Property
Qualifying residential property outside the UK can affect whether the higher rates apply.
Ignoring the Circumstances of a Joint Buyer
One purchaser’s existing property ownership can affect the SDLT treatment of the whole transaction.
Applying One Rate to the Entire Purchase Price
Residential SDLT is calculated progressively across price bands.
Treating the £40,000 Rule as the General SDLT Threshold
The £40,000 figure is important to the additional-property rules. It is not the same thing as the ordinary residential SDLT threshold.
Assuming a Limited Company Avoids the Surcharge
Companies generally face the higher rates on qualifying residential purchases.
Forgetting the Refund Deadline
Selling a former main residence can create a refund opportunity, but HMRC still imposes a deadline for making the claim.
Leaving the Calculation Until Completion
SDLT should be included in the cash-to-complete calculation at the beginning of the transaction, particularly for landlords and investors.
Planning the Finance for a Second Home or Buy-to-Let
Stamp duty is only one part of the capital required to purchase another property.
Your overall funding requirement may also depend on the deposit, mortgage product, valuation, legal costs, lender fees, property condition and the date by which the transaction must complete.
For a rental property, the lender may also assess expected rent, loan-to-value and whether you are borrowing personally or through a company.
If the property is suitable for longer-term rental finance, explore buy-to-let mortgages.
If the transaction has a short completion deadline, involves an auction or needs to complete before longer-term finance is available, bridging finance may instead be relevant.
Lockwell Finance can review the financing side of the property transaction. For a definitive assessment of your SDLT liability, reliefs or exemptions, speak to your conveyancer or a suitably qualified property-tax adviser.
Frequently Asked Questions
What is stamp duty on a second home?
In England and Northern Ireland, buying an additional residential property can trigger higher Stamp Duty Land Tax rates. These are normally five percentage points above the standard residential rates.
What are the current stamp duty rates for a second home?
From 1 April 2025, the additional-property SDLT rates are 5% up to £125,000, 7% from £125,001 to £250,000, 10% from £250,001 to £925,000, 15% from £925,001 to £1.5 million and 17% above £1.5 million.
How much stamp duty is payable on a £300,000 second home?
Using the higher additional-property rates, SDLT on a £300,000 purchase in England or Northern Ireland is £20,000.
That consists of £6,250 on the first £125,000, £8,750 on the next £125,000 and £5,000 on the final £50,000.
Do second-time buyers always pay second-home stamp duty?
No.
If you have sold your previous main home and are purchasing another property to replace it, you may pay the standard residential rates instead.
The higher rates are more likely to apply where you retain the previous property.
Do I pay extra stamp duty if I already own a property abroad?
Potentially, yes.
Qualifying residential property owned outside the UK can count when determining whether the property you are buying will be an additional property.
Can I claim back the second-home stamp-duty surcharge?
You may be able to claim a refund where you paid the higher rates because you bought your new main residence before selling your previous one, and you subsequently dispose of the previous main home within three years.
Claim deadlines also apply.
Is there a legitimate way to avoid second-home stamp duty?
The higher rates do not apply in every transaction, but there is no general loophole allowing buyers to opt out of SDLT when it is legally due.
Whether a lower rate applies depends on matters such as main-residence replacement, the property type, purchase value and the precise ownership position.
Does second-home stamp duty apply to buy-to-let properties?
Usually, if buying the rental property means you will own more than one qualifying residential property.
This is why landlords should include SDLT in their acquisition budget before making an offer.
Do limited companies pay the second-home rates?
Companies generally pay the higher residential rates on qualifying residential property purchases of £40,000 or more. Additional corporate-property rules can also apply in certain circumstances.
Do non-UK residents pay an additional surcharge?
A separate 2% non-UK resident SDLT surcharge can apply to residential purchases in England and Northern Ireland. Where applicable, it can be charged in addition to the higher rates for additional properties.
When must stamp duty be paid?
An SDLT return and the tax due normally need to reach HMRC within 14 days of completion. A solicitor or conveyancer usually deals with this as part of the purchase.
Final Takeaway
For most people who already own a residential property, buying another home in England or Northern Ireland means budgeting for the higher SDLT rates.
The most important points are to establish exactly what property each buyer will own at completion, determine whether the new property replaces a main residence and calculate the SDLT before committing your available cash to the purchase.
If you temporarily own two homes because your previous main residence has not yet sold, remember that a refund may be available after the sale, provided HMRC’s conditions and claim deadlines are met.
For landlords and property investors, SDLT should be assessed alongside the deposit, mortgage, legal costs and wider transaction budget. Lockwell Finance can help with the property-finance side of the purchase, while your conveyancer or qualified tax adviser should confirm the final SDLT treatment.
