
Refurbishment Finance Liverpool
Short-term property finance for Liverpool purchases, refinances and planned improvement works — structured around the property, the works budget, the required timeline and a credible repayment strategy.

What matters before looking for a lender.
The strongest starting point is a clear picture of the property, proposed work, funding requirement and intended exit.
Property address, type, current condition and purchase price or value.
A realistic schedule of works with an itemised refurbishment budget.
Required loan amount, available deposit or equity and target deadline.
An evidenced strategy for repaying or refinancing the short-term facility.
Finance the property and the refurbishment plan.
Refurbishment finance is commonly used where a property needs work before it can be sold, refinanced or moved onto suitable longer-term mortgage lending.
A Liverpool property that needs significant improvement may not be suitable for an ordinary mortgage in its current condition. A refurbishment bridging facility can provide short-term funding while the agreed works are completed.
The available structure depends on the complete transaction rather than the postcode alone. Lenders may consider the purchase price, current value, proposed works, deposit or equity, completed value, borrower profile, project timetable and proposed exit.
When refurbishment finance may be considered in Liverpool.
Each case is assessed individually. These are common situations where short-term property finance may be explored.
Auction purchases
A fixed auction completion date may require a short-term finance route where the property also needs work before longer-term lending is suitable.
Properties needing substantial repairs
Missing facilities, poor condition or essential repairs can affect whether an ordinary mortgage is suitable at the point of purchase.
Buy, improve and refinance
Short-term finance can provide the bridge between acquiring the property and applying for appropriate longer-term finance once the project is complete.
Buy, refurbish and sell
The proposed resale exit should be supported by a realistic works programme, completed-value assumptions and sufficient contingency.
Rental property improvements
Landlords may use short-term finance while completing work before letting the property or refinancing onto suitable Buy-to-Let finance.
More complex renovation projects
Reconfiguration, conversion or structural alterations may require closer assessment of the works, permissions, experience, valuation and funding structure.
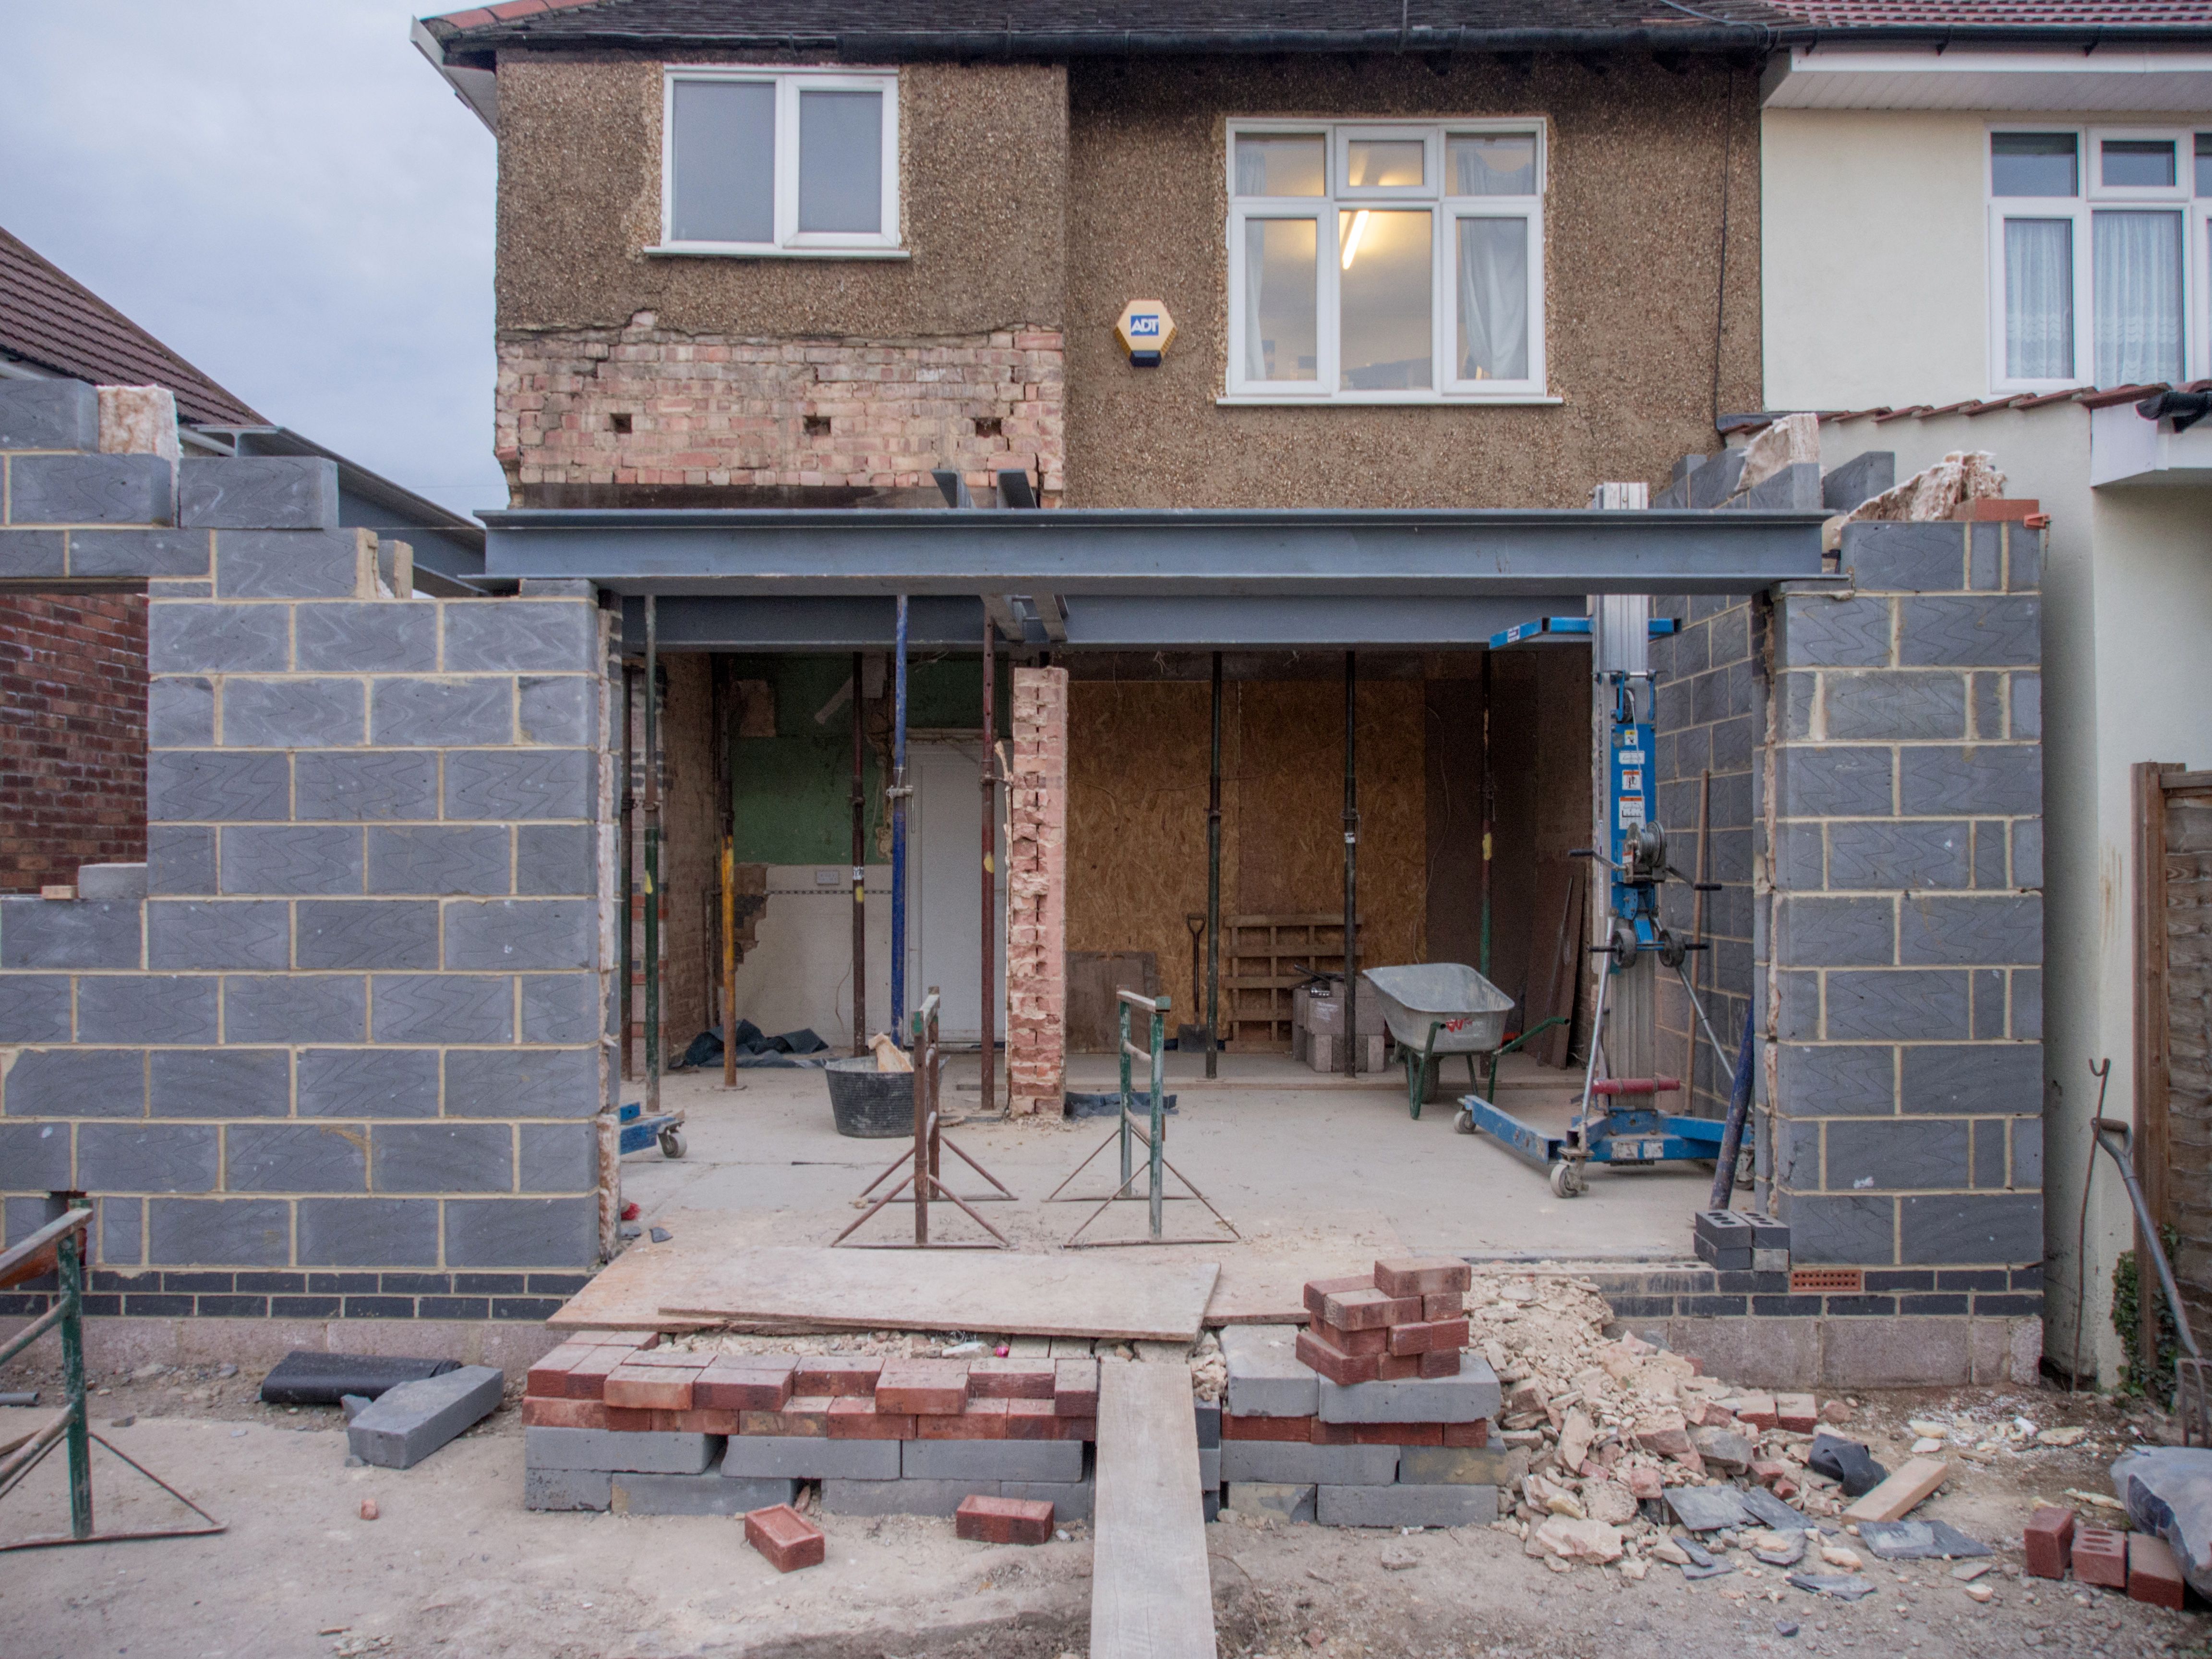
Light and heavy refurbishment are not assessed in the same way.
There is no single definition used by every lender. The works should therefore be described accurately rather than forced into a category based only on the headline budget.
Cosmetic improvements
Decoration, flooring, replacement kitchens, bathrooms and similar non-structural improvements.
Essential repairs
Roofing, heating, plumbing, electrical work and repairs that affect the property's condition or suitability.
Structural or conversion work
Significant alterations, conversions or layout changes can require additional reports, permissions or a different finance route.
How can a refurbishment budget be structured?
The property advance and the money required for the works do not always follow the same structure. The arrangement depends on the lender, property, borrower and complexity of the project.
Works funded separately
Some transactions require the borrower to provide refurbishment capital separately from the property-secured facility.
Works included in the facility
Some lenders may include an element for proposed works, subject to their criteria and the overall project structure.
Funds released in stages
More complex refurbishment projects can involve retained or staged funding and further assessment as the work progresses.
What lenders review before a refurbishment facility is agreed.
Refurbishment finance is assessed as a complete transaction. The security, applicant, works programme, funding requirement and exit need to make sense together.
- 01 The property: location, tenure, construction, condition, current value and marketability.
- 02 The funding requirement: purchase or refinance amount, deposit, existing debt and works capital.
- 03 The works: detailed scope, budget, contractors, professional fees, permissions and contingency.
- 04 The applicant: borrowing structure, relevant experience, source of funds and wider financial position.
- 05 The exit: how the short-term facility will be repaid and what evidence supports that route.
How the refurbishment finance process works.
Preparing the transaction clearly from the outset can reduce avoidable questions and make it easier to determine which lender routes are realistic.
Describe the project
Share the Liverpool property, required loan, borrower structure, proposed works, budget, deadline and intended exit.
Review the structure
The transaction can be considered against lender appetite, security, refurbishment scope, valuation and repayment strategy.
Prepare the application
Supporting documents are organised and the valuation, underwriting and legal stages can begin.
Complete the facility
Once lender conditions, valuation and legal requirements are satisfied, the facility can move to completion.
What should you send for an initial review?
A clear project summary allows the likely funding routes to be assessed more effectively.
Address, property type, tenure, current condition, purchase price and estimated value.
Amount required, available deposit or equity, existing secured debt and available works capital.
Itemised improvements, quotations, professional fees, permissions where applicable and contingency.
Purchase deadline, planned start date, works duration and expected exit date.
Whether you intend to borrow personally or through a company or SPV, together with supporting financial information.
Rental appraisal, resale evidence, refinance assumptions or another supportable repayment source.
The exit strategy is central to refurbishment finance.
A refurbishment bridge is temporary finance. The application should explain from the beginning how the facility is expected to be repaid.
A refinance exit should consider the completed property, valuation, rental position where relevant, borrower profile and criteria of the intended longer-term lender.
A sale exit should use realistic valuation assumptions and allow sufficient time for marketing and legal completion. An alternative route can also be important if the project takes longer than planned.
What clients have said.
“Lockwell Finance made the refurbishment process seamless and stress-free. Highly recommend!”
“Thanks to Lockwell Finance, I was able to transform my property and increase its value significantly.”
“Their team was incredibly supportive and guided me through every step of the financing process.”
Questions about financing a refurbishment.
Exact requirements depend on the property, proposed work, applicant, lender criteria and intended repayment route.
What is refurbishment finance?
Refurbishment finance is short-term property-secured funding used where a property requires improvement before it can be sold, refinanced or moved onto suitable longer-term lending.
Can refurbishment finance be used to buy a Liverpool property that needs work?
Potentially. It may be considered where the property's current condition or the proposed refurbishment makes an ordinary mortgage unsuitable at the outset. The lender will still assess the property, deposit, works, borrower and proposed exit.
Can the loan include the refurbishment costs?
Some facilities can include an element for refurbishment works, while other transactions require those costs to be funded separately. More complex projects can also involve retained or staged funding. The structure depends on the lender and project.
What is the difference between light and heavy refurbishment?
Lender definitions vary. Cosmetic and straightforward non-structural improvements are usually assessed differently from structural alterations, major reconfiguration, extensions and conversion projects.
Can refurbishment finance be used for an auction purchase?
It may be suitable where an auction property needs work and the transaction has a fixed completion deadline. Any auction deadline should be included in the initial project brief because valuation, underwriting and legal work still need to be completed.
Can I apply through a limited company or SPV?
Company and SPV applications may be possible depending on the lender and transaction. Include the intended borrower structure when discussing the project.
How quickly can refurbishment finance complete?
There is no single completion period for every case. Timing depends on factors including valuation availability, legal work, property complexity, lender requirements and how quickly the required documents can be provided.
What should I send Lockwell Finance first?
Start with the Liverpool property details, purchase price or value, required loan, available deposit or equity, proposed works, budget, borrower structure, target completion date and intended exit.
Get a clearer view of your Liverpool refurbishment finance options.
Share the property, proposed works, budget, required amount, borrower structure, deadline and intended exit strategy.
Built by property investors, for property investors.
Monday–Friday
9:00am–6:00pm