
Birmingham refurbishment finance
Refurbishment Finance in Birmingham
Short-term property finance for Birmingham landlords, investors and developers purchasing or refinancing property that requires improvement before sale, letting or longer-term refinance.
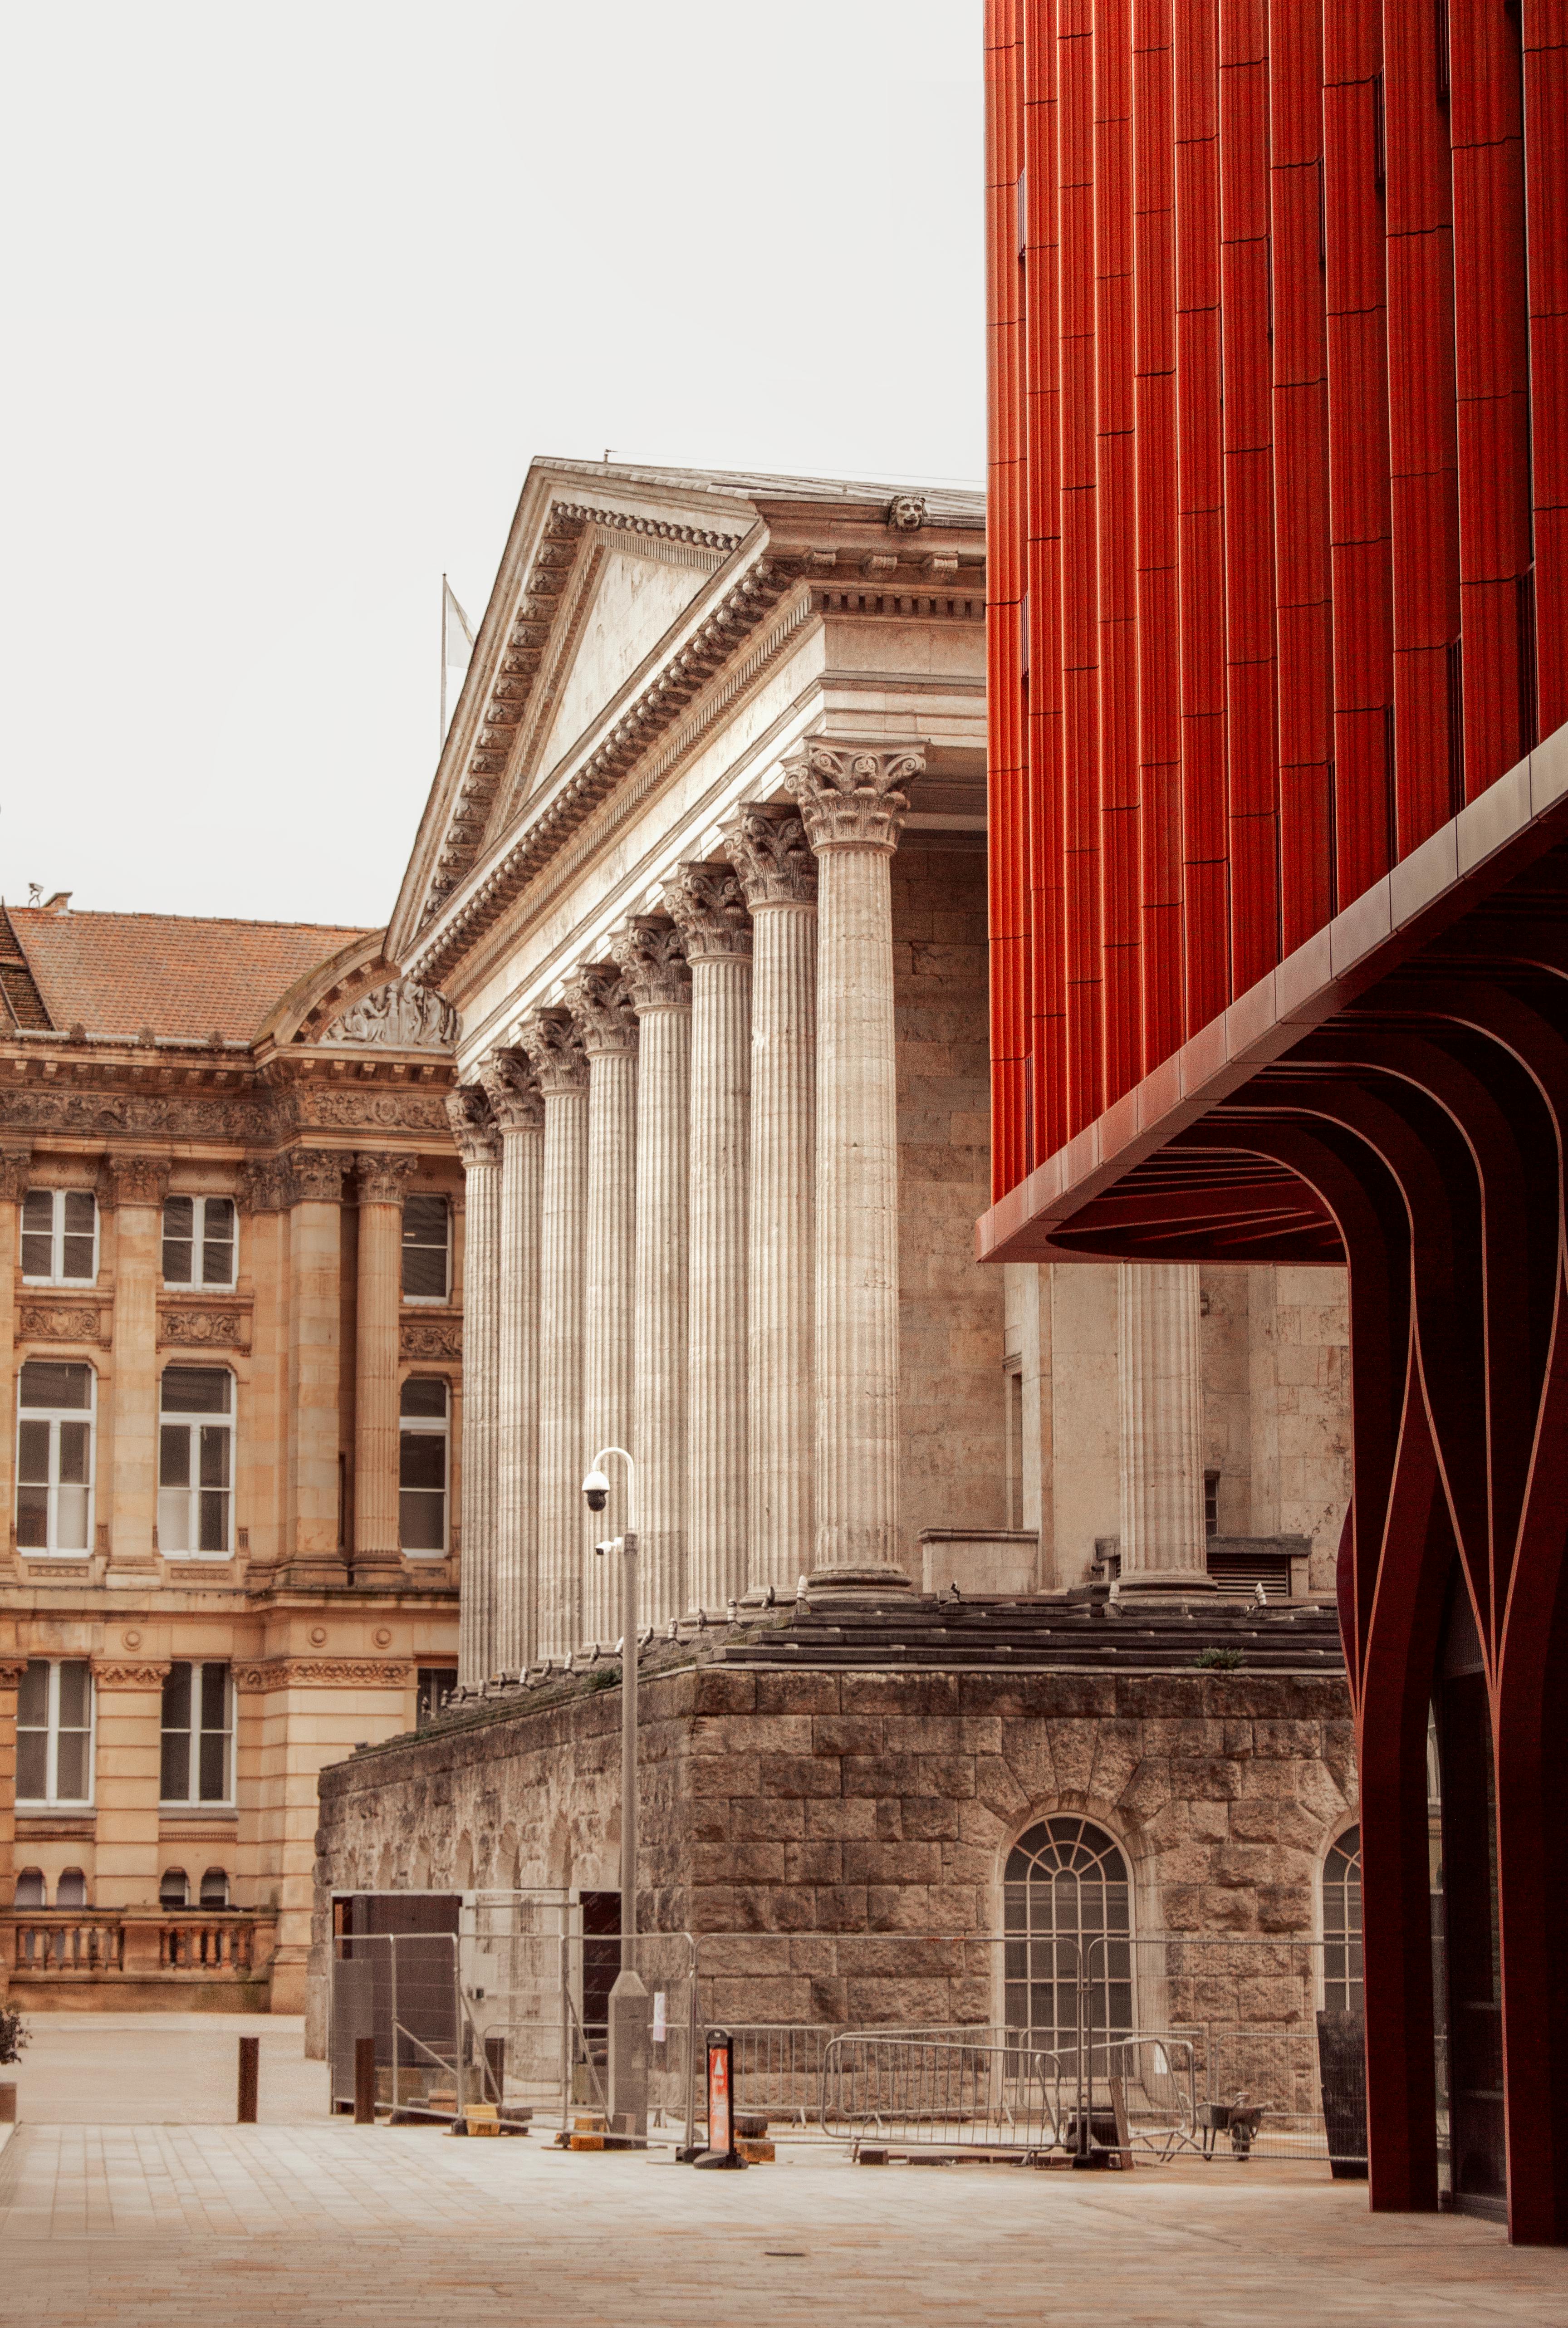
Property address, type, condition and purchase price or current value
Clear schedule of works with a realistic refurbishment budget
Required finance, available deposit or equity and project deadline
Planned repayment through sale, refinance or another evidenced exit
In straightforward terms
Finance the property and the refurbishment plan.
Refurbishment finance is short-term property funding used when a property requires work before it can be sold, refinanced or moved onto suitable longer-term lending.
A property that needs significant improvement may not be suitable for a conventional mortgage at the outset. A refurbishment bridge can provide a temporary route while the planned work is completed.
The finance is assessed around the whole transaction rather than the refurbishment budget in isolation. The property, purchase or refinance position, deposit, works, borrower, timetable, completed property and repayment strategy all need to fit together.
Common project situations
When refurbishment finance may be considered.
Short-term funding may be relevant where property condition, planned works or transaction timing makes conventional long-term lending unsuitable at the start.
Auction purchases
An auction purchase may have a fixed contractual completion date before the property is ready for longer-term mortgage finance.
Properties needing significant work
Repairs, missing facilities or poor condition can make a property unsuitable for mainstream mortgage lending until the work has been completed.
Buy, refurbish and refinance
Short-term funding can be considered during the refurbishment before an application for appropriate longer-term finance on the completed property.
Buy, refurbish and sell
A sale-led strategy should be supported by a sensible works programme, realistic valuation assumptions and enough time for the eventual disposal.
Rental property improvements
Refurbishment finance may support improvements required before the property can be let or moved onto suitable landlord finance.
Commercial or mixed-use refurbishment
Appropriate commercial and mixed-use properties requiring improvement can also be considered, depending on the security, works and proposed exit.

Understanding the works
Light and heavy refurbishment are assessed differently.
Lender definitions vary, so the project should be described through the actual work involved rather than relying only on a label or total budget.
Cosmetic improvements. Decoration, replacement kitchens, bathrooms, flooring and similar non-structural improvements.
Essential repairs. Roofing, heating, plumbing, electrical work and repairs affecting the property's condition.
Layout changes. Reconfiguration or conversion work may require additional assessment of permissions, budget and experience.
Structural projects. Extensions and significant structural alterations can involve more detailed underwriting or staged funding.
Funding the works
How can the refurbishment budget be structured?
The advance used for the property and the capital needed for the works do not necessarily follow the same structure. The position depends on the lender, property, applicant and scope of the project.
Works funded separately
Some transactions require the borrower to provide refurbishment capital separately from the property-secured facility.
Works included within the facility
Some lenders may allow an element of the planned refurbishment cost within the facility, subject to their criteria and the project structure.
Funds released in stages
More substantial projects may involve retained or staged funding, further inspections or additional assessment while the work progresses.
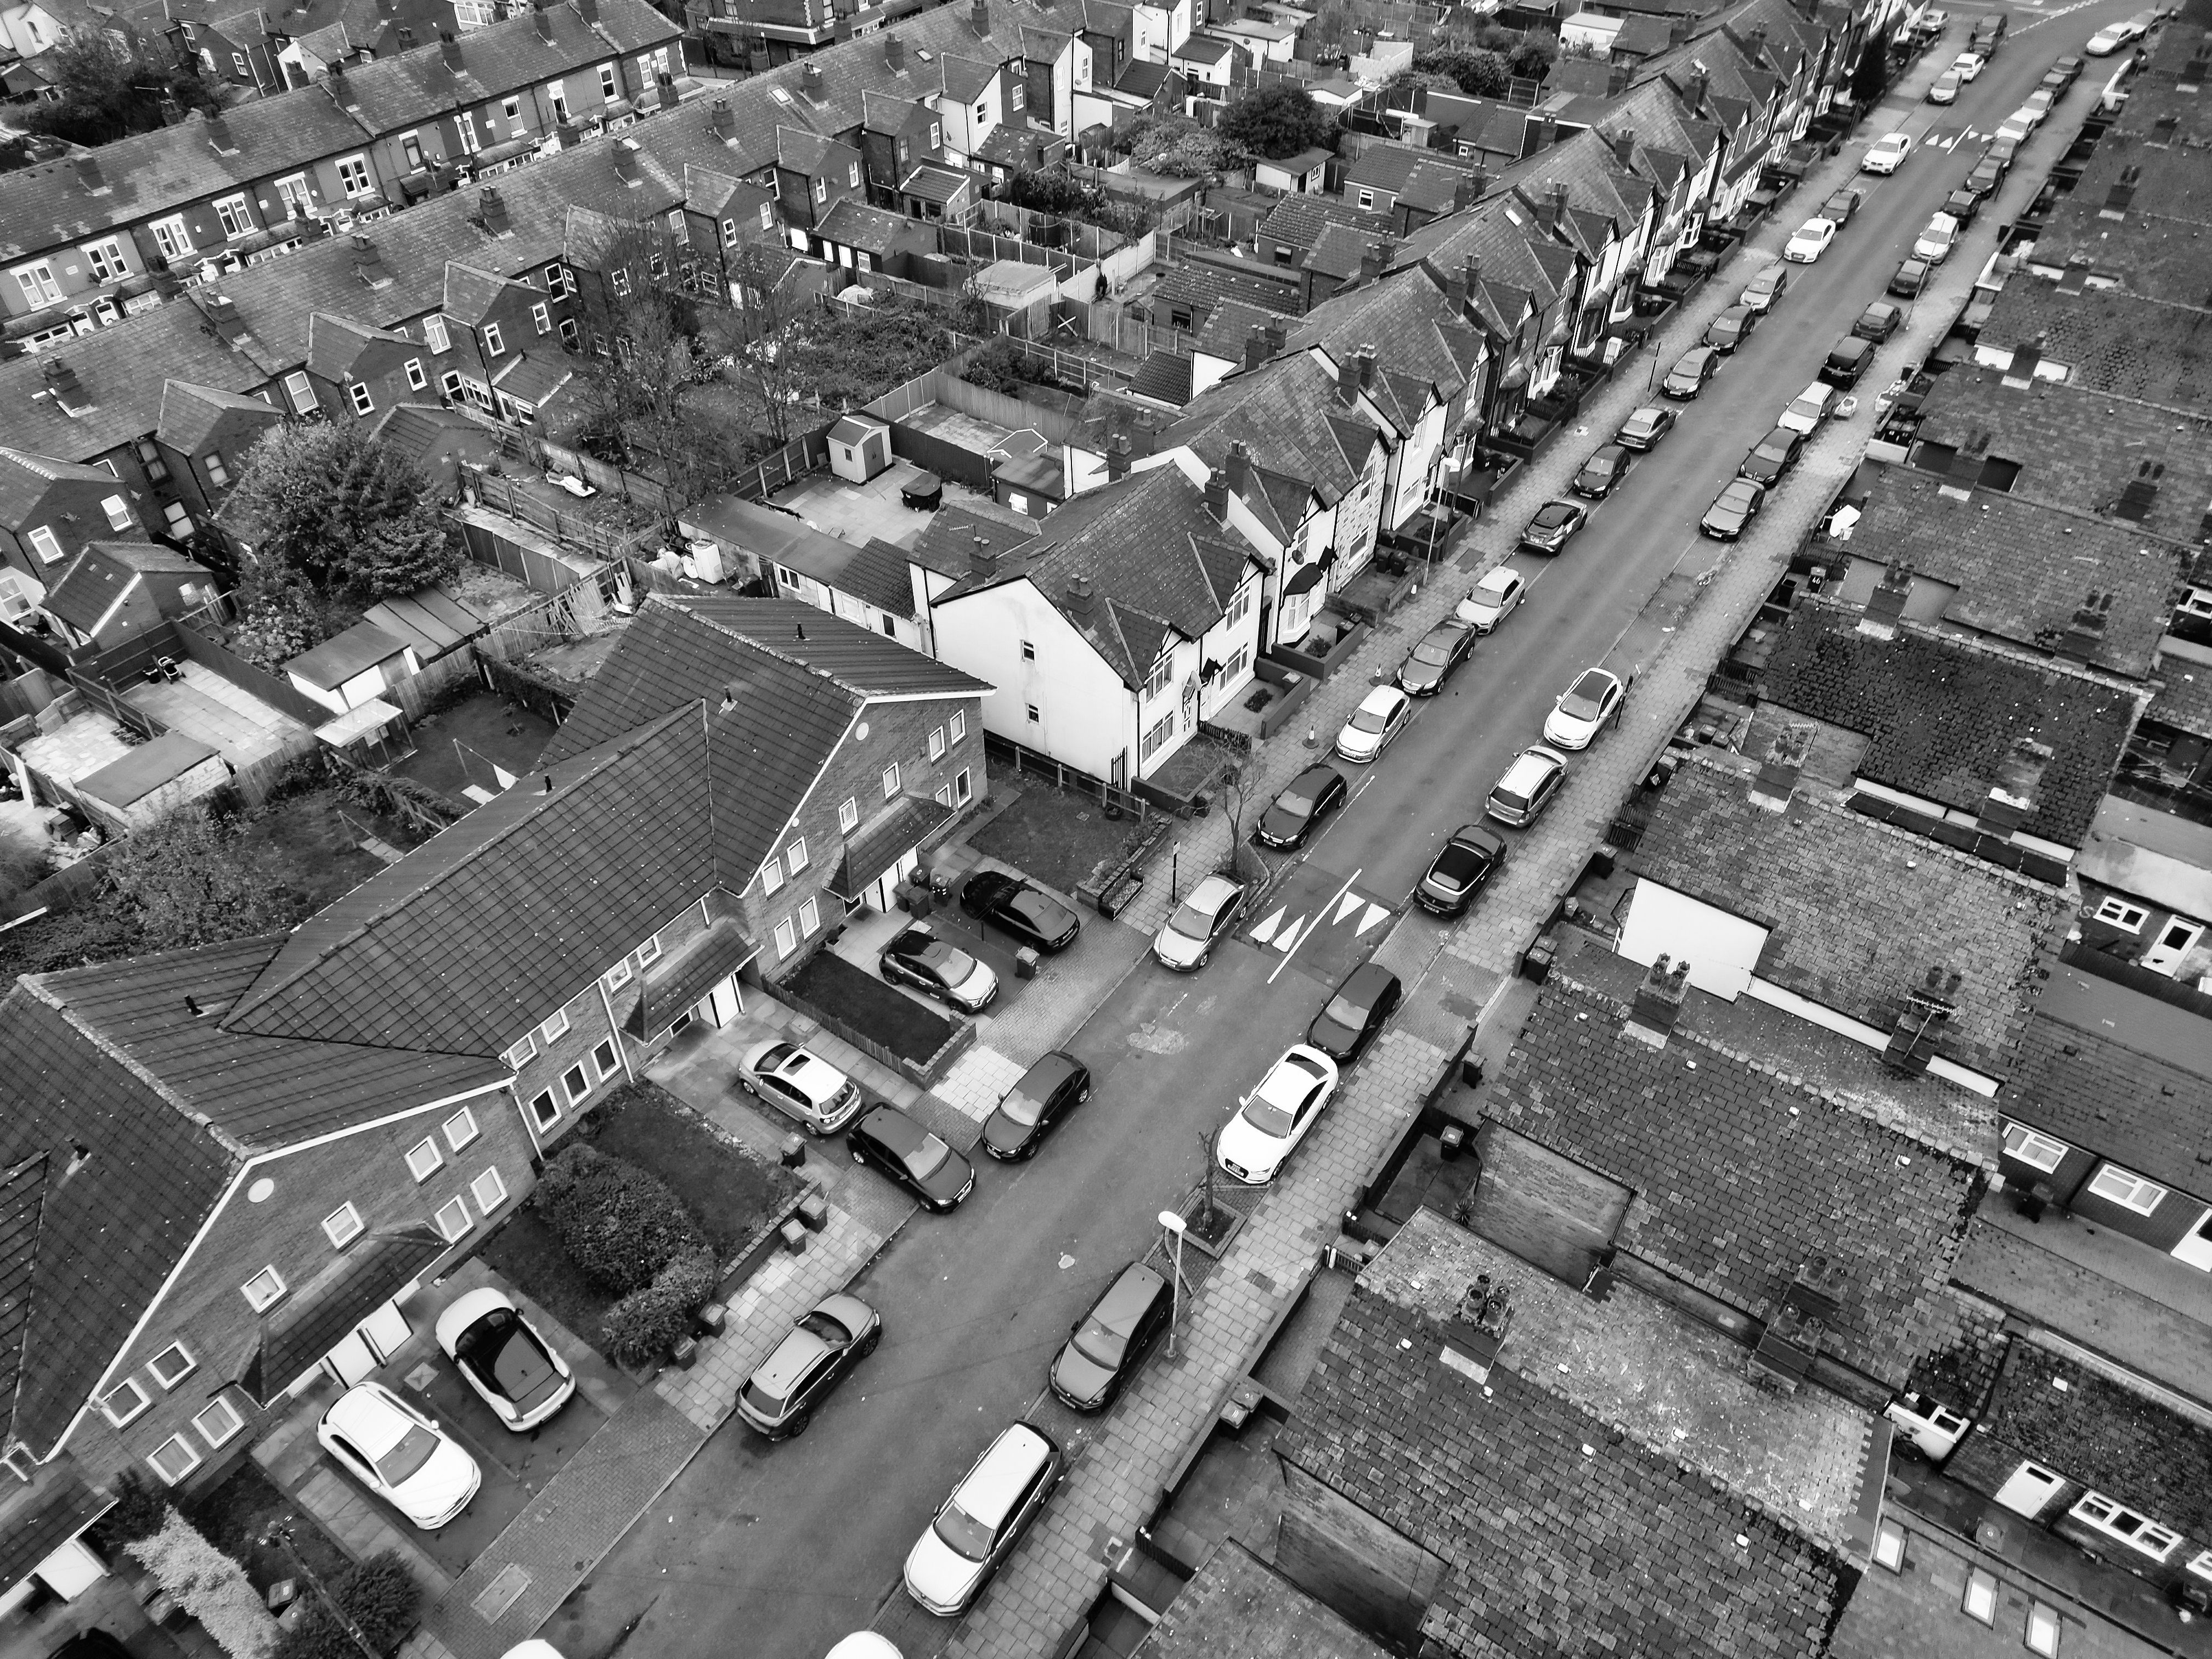
Birmingham property context
Refurbishment projects across Birmingham can look very different.
Birmingham includes city-centre apartments, terraced housing, suburban homes, mixed-use buildings and commercial property. The funding route should therefore be considered against the individual property and works rather than the city name alone.
Location can influence valuation, marketability, rental assumptions and the proposed exit, but postcode is only one part of the lender's assessment. Condition, security, works, leverage and repayment strategy remain central.
How lenders assess the deal
Six areas of the transaction need to support each other.
The security
Property condition, location, construction, tenure, title and marketability.
The funding requirement
Purchase or refinance amount, deposit, existing debt and proposed works funding.
The works programme
Scope, budget, contractors, permissions, expected duration and contingency.
The applicant
Borrower structure, relevant experience, financial position and source of funds.
The finished property
Proposed use, expected condition, valuation assumptions and rental position where relevant.
The exit strategy
How the bridge will be repaid, what supports that route and what alternatives exist.
From enquiry to completion
How the refurbishment finance process works.
Preparing the deal clearly at the beginning helps identify missing information and whether the proposed finance and timetable are realistic.
Describe the project
Share the property, funding requirement, works budget, borrower structure, deadline and planned exit.
Review the structure
The transaction can be considered against the security, refurbishment scope and relevant lender criteria.
Prepare the application
Required documents are organised and the valuation, underwriting and legal stages can move forward.
Complete and deliver
Once lender and legal requirements are satisfied, the facility completes and the refurbishment plan can proceed.
Prepare before applying
What should you send for an initial review?
A concise project summary gives the broker a clearer starting point and makes it easier to identify figures or evidence that still need to be prepared.
Property information
Address, property type, tenure, condition, purchase price and estimated value.
Funding figures
Required amount, deposit or equity, existing debt and available refurbishment capital.
Schedule of works
Itemised improvements, contractor estimates, professional fees, permissions and contingency.
Project timetable
Purchase deadline, proposed start, expected works duration and target exit date.
Borrower information
Identification, financial evidence and company or SPV information where applicable.
Exit evidence
Rental appraisal, resale evidence, refinance assumptions or another supported repayment route.
Plan repayment before borrowing
The exit strategy is central to the application.
Refurbishment bridging is temporary finance. The proposed repayment route therefore needs to be considered from the beginning rather than after the work has been completed.
A refinance exit needs to take account of the completed property, valuation, rent where applicable, borrower circumstances and the criteria of the intended longer-term lender.
A sale exit should be based on realistic value assumptions and allow enough time for marketing and legal completion.
- Sale of the refurbished property
- Refinance onto an appropriate Buy-to-Let mortgage
- Refinance onto other suitable longer-term finance
- Repayment from another clearly evidenced source
Understanding the total cost
What can affect refurbishment bridging terms and costs?
There is no single rate or funding structure that applies to every project. Terms depend on the full transaction, so the complete cost should be considered rather than a headline rate alone.
| Factor | Why it matters | What to prepare |
|---|---|---|
| Loan-to-value | The amount borrowed compared with the property value affects the lender's security position. | Accurate purchase price, valuation and existing debt figures. |
| Property condition | Extensive works or reduced marketability can affect the available lender options. | Property details, photographs and a detailed works schedule. |
| Project complexity | Structural works and more complex alterations can require additional underwriting. | Plans, permissions, contractor information and professional reports where relevant. |
| Loan term | The facility needs to allow sufficient time for the works and the proposed exit. | A realistic programme including suitable contingency. |
| Exit strength | The quality and evidence behind the repayment strategy can influence lender appetite. | Refinance assumptions, rental evidence, resale information or other exit evidence. |
Related finance routes
The right next step depends on what happens after the works.
Questions about the service
Refurbishment finance Birmingham FAQs.
Exact requirements depend on the property, planned work, applicant, valuation, lender criteria and intended repayment route.
How does refurbishment finance work in Birmingham?
Refurbishment finance is typically short-term property-secured funding used while improvement works are completed. The lender considers the property, required loan, deposit or equity, scope of works, budget, borrower and proposed exit together.
Can refurbishment finance cover the cost of the works?
Potentially. Some facilities may include an element for refurbishment costs, while other transactions require the borrower to fund the works separately. More substantial projects may involve retained or staged releases. The structure depends on the lender and project.
What is the difference between light and heavy refurbishment?
Lender definitions vary. Cosmetic or largely non-structural work is generally assessed differently from structural alterations, extensions, conversions and other projects involving greater complexity or additional permissions.
Can finance be considered if the property is not currently mortgageable?
It may be possible where the property's condition prevents conventional mortgage lending at the outset. The lender will still need to be satisfied with the security, works, funding position and credible route to repayment.
Can refurbishment finance be used for a Birmingham auction purchase?
Potentially. Refurbishment bridging may be considered where an auction purchase has a fixed completion deadline and the property requires work before suitable longer-term lending can be arranged.
Can I apply through a limited company or SPV?
Limited-company and SPV applications may be possible, subject to the lender and transaction. Information about the company, its directors or shareholders and the underlying property deal may be required.
Are refurbishment funds always released upfront?
No. The works may be funded separately, included within the facility or released in stages. More complex projects can require additional inspections or evidence before retained funds are released.
What documents should I prepare?
Common requirements can include identification, financial information, property details, the purchase or refinance figures, a schedule of works, contractor estimates, evidence of available funds and information supporting the proposed exit.
Can I refinance onto a Buy-to-Let mortgage after refurbishment?
A Buy-to-Let refinance can be one possible exit where the completed property, rental position, borrower and ownership structure meet the requirements of the intended mortgage lender.
How quickly can refurbishment finance complete?
There is no single completion time for every application. Timing depends on document readiness, valuation, legal work, property complexity and lender underwriting. Any fixed auction or contractual deadline should be explained at the start of the enquiry.
Start with the deal
Get a clearer view of your Birmingham refurbishment finance options.
Share the property, proposed works, budget, required amount, borrower structure, deadline and intended exit. Lockwell Finance can then review the transaction and explain the most realistic next step.
Mortgage and finance availability is subject to status, affordability, valuation, lender criteria and underwriting.