

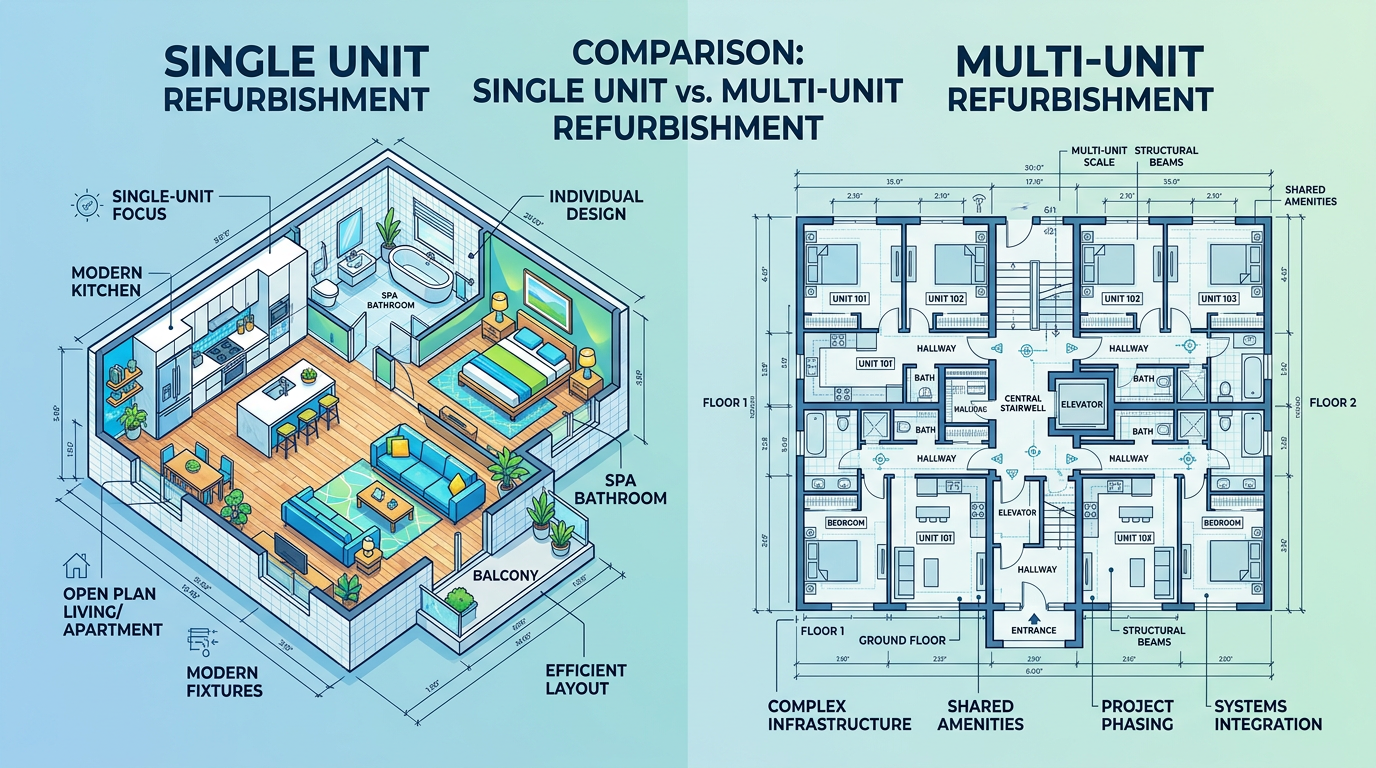
Understanding Refurbishment Bridging Loans
Refurbishment bridging loans are short-term financing options designed to help property investors and developers fund renovation projects. These loans provide quick access to capital, allowing borrowers to undertake refurbishments without the lengthy approval processes typical of traditional mortgages. The primary purpose of refurbishment bridging loans is to bridge the financial gap between the purchase of a property and its subsequent refinancing or sale after renovations are completed.
The benefits of refurbishment bridging loans are numerous. Firstly, they offer speed; funds can often be released within a matter of days, making them ideal for time-sensitive projects. Secondly, they are flexible, accommodating a wide range of refurbishment works, from cosmetic upgrades to structural changes. Borrowers can also leverage the increased value of the property post-renovation to secure a more favorable refinancing option later on. Additionally, these loans are typically secured against the property itself, which means that the lender’s risk is mitigated by the asset’s value.
In summary, refurbishment bridging loans are a vital financial tool for property investors looking to enhance the value of their assets quickly and efficiently. Their ability to provide immediate funding and flexibility makes them an attractive option for both single unit and multi-unit refurbishment projects.
Single Unit Refurbishment Bridging Loans
Single unit refurbishment bridging loans are tailored specifically for projects involving one property, whether it’s a residential home or a single rental unit. These loans are characterized by their straightforward application process, typically requiring less documentation compared to multi-unit loans. The focus on a single property allows for a more streamlined assessment of the loan’s risk and potential return.
Typical use cases for single unit refurbishment bridging loans include:
- Home Renovations: Homeowners looking to renovate their primary residence can use these loans to fund improvements such as kitchen remodels, bathroom upgrades, or extensions.
- Buy-to-Let Investments: Investors purchasing a single rental property may opt for a refurbishment bridging loan to enhance the property’s appeal and rental yield before refinancing or selling.
- Flipping Properties: Investors aiming to buy, renovate, and quickly sell properties for profit often rely on single unit refurbishment loans to finance their projects.
One of the key advantages of single unit refurbishment loans is the speed of approval. Lenders often have less complexity to navigate, allowing for quicker funding. Additionally, these loans typically come with lower fees and interest rates compared to multi-unit loans, making them a cost-effective option for smaller projects.
Moreover, borrowers can benefit from the simplicity of managing a single project. This includes overseeing the renovation work, coordinating with contractors, and ensuring that the project stays on budget and on schedule. With fewer variables to manage, property owners can focus their efforts on maximizing the value of their investment.
Multi-Unit Refurbishment Bridging Loans
Multi-unit refurbishment bridging loans cater to projects involving multiple properties or units, such as apartment blocks or multi-family homes. These loans are designed to accommodate the complexities associated with larger-scale renovations, providing investors with the necessary capital to undertake significant refurbishment works.
Features of multi-unit refurbishment loans include:
- Higher Loan Amounts: Given the larger scope of work, these loans often allow for significantly higher borrowing limits, enabling investors to fund extensive renovations across multiple units.
- Complex Application Process: The application process for multi-unit loans can be more intricate, often requiring detailed project plans, cash flow forecasts, and comprehensive financial documentation.
- Flexible Repayment Options: Lenders may offer various repayment structures, including interest-only periods, to accommodate the cash flow needs of investors during the renovation phase.
Advantages of financing multiple properties through refurbishment bridging loans include:
- Economies of Scale: Investors can benefit from reduced costs per unit when undertaking renovations on multiple properties simultaneously, leading to higher overall profitability.
- Diverse Investment Portfolio: By refurbishing multiple units, investors can diversify their rental income streams, reducing the risk associated with vacancy in any single property.
- Increased Property Value: Renovating multiple units can significantly enhance the overall value of a property portfolio, making it more attractive to future buyers or lenders.
Ultimately, multi-unit refurbishment bridging loans provide a robust financial solution for investors looking to capitalize on larger-scale renovation projects, enhancing both their investment potential and market competitiveness.
Key Differences Between Single and Multi-Unit Loans
When comparing single and multi-unit refurbishment bridging loans, several key differences emerge, particularly in terms of loan terms, interest rates, and repayment structures.
Loan Terms: Single unit loans typically feature shorter terms, often ranging from six months to one year. These loans are designed for quick renovations and subsequent refinancing or resale. In contrast, multi-unit loans may offer longer terms, reflecting the extended timelines often required for larger projects.
Interest Rates: Interest rates for single unit refurbishment loans are generally lower due to the reduced risk associated with lending on a single property. Multi-unit loans, while potentially higher in interest, can still be competitive, especially when considering the higher loan amounts involved. Borrowers should shop around to ensure they secure the best possible rates based on their specific project needs.
Repayment Structures: Single unit loans often come with straightforward repayment structures, typically requiring monthly payments. Multi-unit loans, however, may offer more flexible options, such as interest-only payments during the renovation phase, allowing investors to manage their cash flow more effectively. This flexibility can be crucial in ensuring that projects remain financially viable throughout the refurbishment process.
Additionally, the complexity of the application process differs significantly. Single unit loans usually require less documentation and a simpler approval process, while multi-unit loans demand more detailed financial analysis and project planning. This complexity can lead to longer approval times for multi-unit loans, making it essential for investors to plan accordingly.
In summary, the choice between single and multi-unit refurbishment bridging loans hinges on the scale of the project, the investor’s financial strategy, and the specific needs of the refurbishment. Understanding these differences can help investors make informed decisions that align with their renovation goals and financial capabilities.
Choosing the Right Loan for Your Project
Selecting the appropriate refurbishment bridging loan is crucial for the success of any renovation project. Several factors should be considered when determining whether to pursue a single or multi-unit loan.
Project Scope: The first consideration is the scope of the project. If you are planning to renovate a single property, a single unit refurbishment bridging loan may be the most efficient choice. However, if your project involves multiple units or properties, a multi-unit loan will likely be necessary to secure adequate funding.
Budget: Assessing your budget is essential. Single unit loans generally come with lower fees and interest rates, making them more accessible for smaller projects. Conversely, multi-unit loans may involve higher costs but can also provide greater potential returns through enhanced property values and rental income.
Timelines: Consider the timelines for your project. Single unit loans often allow for quicker access to funds, which is ideal for time-sensitive renovations. Multi-unit loans, while potentially offering more substantial financing, may take longer to process due to their complexity. Ensure that your project timelines align with the loan approval process.
Future Plans: Think about your long-term goals. If you plan to expand your property portfolio or undertake additional renovations in the future, a multi-unit refurbishment bridging loan may provide the flexibility and funding needed to support your growth strategy.
Ultimately, the right loan choice will depend on a careful evaluation of these factors, aligning your financial needs with your renovation objectives. Engaging with a financial advisor or bridging loan specialist can provide valuable insights and help you navigate the decision-making process effectively.
Application Process for Refurbishment Bridging Loans
The application process for refurbishment bridging loans can vary significantly between single and multi-unit projects. Understanding the steps involved can streamline your experience and increase the likelihood of approval.
Step 1: Initial Consultation – Begin by consulting with a bridging loan specialist to discuss your project details and financing needs. This initial conversation will help determine whether a single or multi-unit loan is appropriate for your situation.
Step 2: Documentation Preparation – Gather the necessary documentation. For single unit loans, this may include basic identification, property details, and a brief project plan. Multi-unit loans will require more extensive documentation, such as detailed financial statements, cash flow forecasts, and comprehensive project plans.
Step 3: Application Submission – Submit your application along with the required documentation. Ensure that all information is accurate and complete to avoid delays in processing.
Step 4: Lender Assessment – The lender will assess your application, reviewing your financial history, project viability, and the value of the property. This assessment may involve a property valuation to determine its worth post-refurbishment.
Step 5: Loan Offer – If approved, the lender will provide a loan offer detailing the terms, interest rates, and repayment structure. Review this offer carefully and consider seeking advice before accepting.
Step 6: Completion and Fund Release – Once you accept the loan offer, the lender will finalize the legal documentation, and funds will be released for your project. For multi-unit loans, this process may take longer due to the complexity of the financing.
Throughout the application process, maintain open communication with your lender and provide any additional information they may request promptly. This proactive approach can help expedite the approval process and ensure a smooth funding experience.
Case Studies: Successful Refurbishment Projects
Examining successful refurbishment projects can provide valuable insights into the effective use of refurbishment bridging loans, whether for single or multi-unit properties.
Single Unit Case Study: A homeowner in London purchased a dilapidated Victorian terrace for £400,000. They secured a single unit refurbishment bridging loan of £100,000 to fund extensive renovations, including a new kitchen, bathroom, and structural repairs. Within six months, the property was valued at £550,000, allowing the homeowner to refinance at a lower interest rate and recover their investment. The quick access to funds enabled them to complete the project efficiently and capitalize on the rising property market.
Multi-Unit Case Study: A property investor acquired a block of four flats in Manchester for £800,000. They opted for a multi-unit refurbishment bridging loan of £200,000 to renovate the flats, updating interiors and enhancing energy efficiency. The investor’s strategy involved increasing rental yields and overall property value. After completing the renovations, the block was valued at £1.2 million, providing the investor with significant equity to refinance and expand their portfolio. This case illustrates how multi-unit refurbishment loans can facilitate substantial financial growth through strategic renovations.
Both case studies highlight the importance of careful planning, timely execution, and effective use of refurbishment bridging loans to achieve successful outcomes in property renovation projects.
Expert Tips for Securing the Best Rates
Securing favorable rates on refurbishment bridging loans can significantly impact the overall cost of your project. Here are some expert tips to help you negotiate the best terms:
- Improve Your Credit Score: A higher credit score can lead to better interest rates. Before applying, review your credit report and address any discrepancies or outstanding debts.
- Provide Comprehensive Documentation: Lenders appreciate thoroughness. Submit complete and accurate documentation to demonstrate your financial stability and project viability.
- Shop Around: Don’t settle for the first offer. Compare rates and terms from multiple lenders to ensure you secure the most competitive deal.
- Consider a Larger Deposit: Offering a larger deposit can reduce the lender’s risk and may result in lower interest rates. If possible, consider increasing your initial investment.
- Engage a Broker: A bridging loan broker can provide valuable insights and access to exclusive deals. They can help you navigate the market and find the best rates tailored to your needs.
By following these tips and remaining proactive in your loan search, you can enhance your chances of securing the best rates for your refurbishment bridging loan, ultimately maximizing your project’s profitability.
Frequently Asked Questions
What is a refurbishment bridging loan?
A refurbishment bridging loan is a short-term loan for property renovation projects, providing quick access to funds for refurbishments.
What are the benefits of single unit refurbishment loans?
Single unit refurbishment loans are easier to manage and typically feature a quicker approval process, making them ideal for smaller projects.
How do multi-unit refurbishment loans differ?
Multi-unit refurbishment loans offer higher financing amounts and may involve more complex applications due to the larger scope of work.
What factors should I consider when choosing a loan?
Consider project scope, budget, and timelines when selecting the appropriate refurbishment bridging loan for your needs.
Can I use a refurbishment bridging loan for multiple properties?
Yes, multi-unit loans are specifically designed for projects involving multiple properties, allowing for extensive renovations across several units.
