

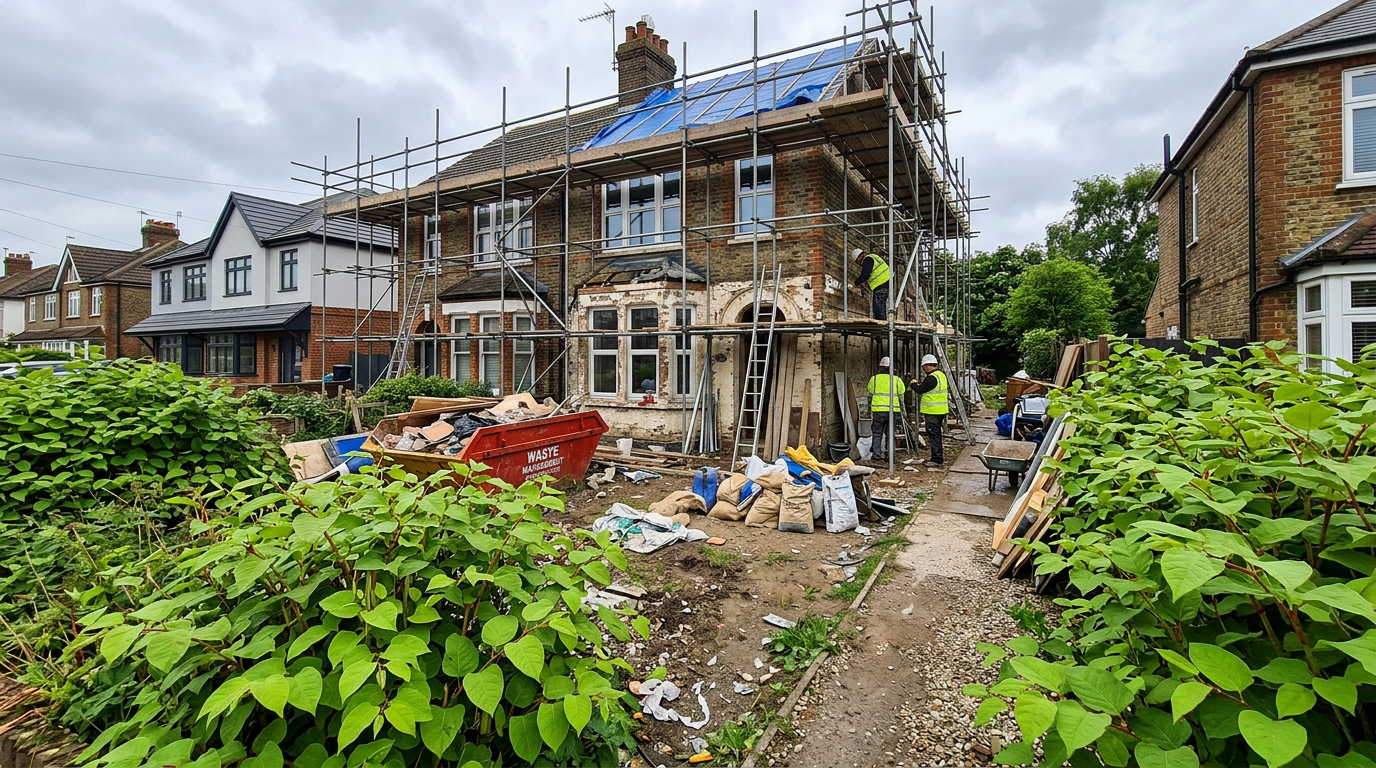
Understanding Japanese Knotweed and Its Impact on Property
Japanese knotweed (Fallopia japonica) is an invasive plant species that poses significant challenges for property owners in the UK. Originally introduced as an ornamental plant, it is now notorious for its rapid growth and ability to damage structures. The plant can grow up to 3 meters in height and has extensive root systems that can penetrate foundations, walls, and drainage systems, leading to costly repairs.
The presence of Japanese knotweed can severely affect property values. Properties with this invasive plant are often viewed as high-risk investments, leading to lower market prices. Surveys indicate that properties affected by knotweed can lose up to 20% of their value, depending on the extent of the infestation and the effectiveness of the removal plan. Additionally, mortgage lenders may refuse to finance properties with active infestations, further complicating sales and purchases.
Legal implications also arise from the presence of Japanese knotweed. Under the Wildlife and Countryside Act 1981, it is illegal to plant or cause Japanese knotweed to grow in the wild. Property owners are responsible for controlling and managing this invasive species on their land. Failure to do so can result in legal action from neighbors or local authorities, especially if the knotweed spreads to adjacent properties. Therefore, addressing Japanese knotweed is not only a financial concern but also a legal obligation for property owners.
What is a Refurbishment Bridging Loan?
A refurbishment bridging loan is a short-term financing option designed to fund renovation projects, particularly for properties that require significant repairs or upgrades. These loans are typically used by property investors and developers who need immediate access to funds to complete refurbishments before selling or refinancing the property.
Unlike traditional mortgages, refurbishment bridging loans are more flexible and faster to secure, making them ideal for urgent renovation needs. Traditional loans often involve lengthy approval processes and stringent credit checks, while bridging loans can be approved in a matter of days, allowing borrowers to act quickly on investment opportunities.
When considering a bridging loan for refurbishment, several factors come into play. These include the property’s current condition, the estimated costs of refurbishment, and the anticipated increase in value post-renovation. Borrowers should also evaluate their exit strategy, whether it involves selling the property or refinancing into a long-term mortgage once the refurbishment is complete.
The Importance of Knotweed Removal Finance
Financing knotweed removal is crucial for property owners facing the challenges of this invasive species. The costs associated with effective removal can be substantial, often ranging from £1,000 to over £10,000 depending on the infestation’s severity and the methods used. Without proper financing, property owners may struggle to address the issue promptly, risking further damage and financial loss.
Cost factors involved in knotweed removal include the assessment of the infestation, the treatment plan, and ongoing monitoring to ensure complete eradication. Professional removal services often employ various methods, such as herbicide treatments, excavation, or a combination of both, which can influence overall costs. Additionally, property owners may need to budget for potential structural repairs caused by the knotweed’s growth.
Ignoring the presence of Japanese knotweed can lead to significant financial risks. Properties with active infestations may face decreased market values, difficulty securing financing, and potential legal liabilities. By investing in knotweed removal finance, property owners can mitigate these risks, protect their investments, and enhance the property’s marketability.
How to Secure a Bridging Loan for Knotweed Affected Properties
Securing a refurbishment bridging loan for properties affected by Japanese knotweed involves several steps. First, borrowers should assess their financial needs and the estimated costs associated with both the knotweed removal and the refurbishment project. This assessment will help determine the loan amount required.
The application process typically begins with selecting a lender that specializes in bridging finance. Borrowers should gather necessary documentation, including proof of income, details of the property, and a comprehensive plan for the refurbishment and knotweed removal. Lenders will evaluate the property’s current condition, the proposed treatment plan for the knotweed, and the expected increase in value post-refurbishment.
Factors that lenders consider for knotweed properties include the severity of the infestation, the effectiveness of the proposed removal plan, and the borrower’s overall financial profile. Lenders may also require a professional survey to assess the property’s condition and the extent of the knotweed issue. It’s essential for borrowers to present a clear and actionable plan to demonstrate their commitment to resolving the knotweed problem and completing the refurbishment.
Case Studies: Successful Refurbishments After Knotweed Removal
Real-life examples of properties refurbished after knotweed removal highlight the potential for successful investments. One notable case involved a Victorian terrace in London that had been significantly devalued due to a severe knotweed infestation. The property owner secured a refurbishment bridging loan to finance the removal of the knotweed and undertake necessary renovations.
After professional removal and a comprehensive refurbishment, the property’s value increased by 30%, allowing the owner to sell it for a substantial profit. This case illustrates the financial benefits of addressing knotweed issues promptly and effectively.
Another example involved a buy-to-let investor who purchased a property with a known knotweed problem. By financing the removal and refurbishment through a bridging loan, the investor was able to enhance the property’s appeal and subsequently secure a higher rental yield. The successful removal of knotweed not only improved the property’s condition but also attracted quality tenants, resulting in a steady income stream.
These case studies demonstrate that with the right financing and a strategic approach, property owners can turn knotweed challenges into profitable opportunities, reinforcing the importance of addressing such issues head-on.
Choosing the Right Lender for Your Bridging Loan
Choosing the right lender for a refurbishment bridging loan is critical to ensuring a smooth financing process. When evaluating potential lenders, property owners should consider several factors:
- Experience with Knotweed Properties: Select lenders who have experience dealing with properties affected by Japanese knotweed. They will better understand the unique challenges and financing needs associated with such properties.
- Interest Rates and Terms: Compare interest rates and repayment terms among different lenders. Look for competitive rates that align with your financial strategy and ensure that the terms are manageable.
- Fees and Hidden Costs: Be aware of any fees associated with the loan, including arrangement fees, valuation fees, and early repayment penalties. Understanding the total cost of borrowing will help you make informed decisions.
- Customer Service: A lender’s responsiveness and willingness to assist throughout the process can significantly impact your experience. Choose a lender known for excellent customer service and support.
By carefully assessing these factors, property owners can select a lender that meets their needs and facilitates a successful refurbishment project.
The Future of Property Investments with Knotweed Concerns
As property investments continue to evolve, the presence of Japanese knotweed remains a significant concern for investors and homeowners alike. Trends indicate that more buyers are becoming aware of the implications of knotweed, leading to increased scrutiny during property transactions. This awareness can impact property values, making it essential for owners to proactively address any infestations.
To mitigate risks associated with knotweed, property owners should consider implementing regular inspections and maintenance plans. Engaging with professionals who specialize in knotweed management can help identify potential issues early, allowing for timely intervention and effective removal strategies.
Long-term strategies for property owners include educating themselves on the legal obligations surrounding knotweed and staying informed about best practices for management and removal. By fostering a proactive approach, property owners can protect their investments and maintain property values, even in the face of knotweed challenges.
FAQs About Japanese Knotweed Refurbishment Bridging Loans
What is a Japanese knotweed refurbishment bridging loan?
A short-term loan for refurbishing properties affected by Japanese knotweed.
How can I finance knotweed removal?
Through specific loans designed for refurbishment and knotweed removal costs.
What should I consider when applying for a bridging loan?
Interest rates, repayment terms, and the lender’s experience with knotweed properties.
Are there risks associated with buying a property with knotweed?
Yes, including potential decreases in property value and legal liabilities.
How long does it take to remove Japanese knotweed?
Typically several months, depending on the extent of the infestation and removal methods.
Can I get a bridging loan if my property has knotweed?
Yes, but lenders may require a detailed plan for removal and refurbishment.
