

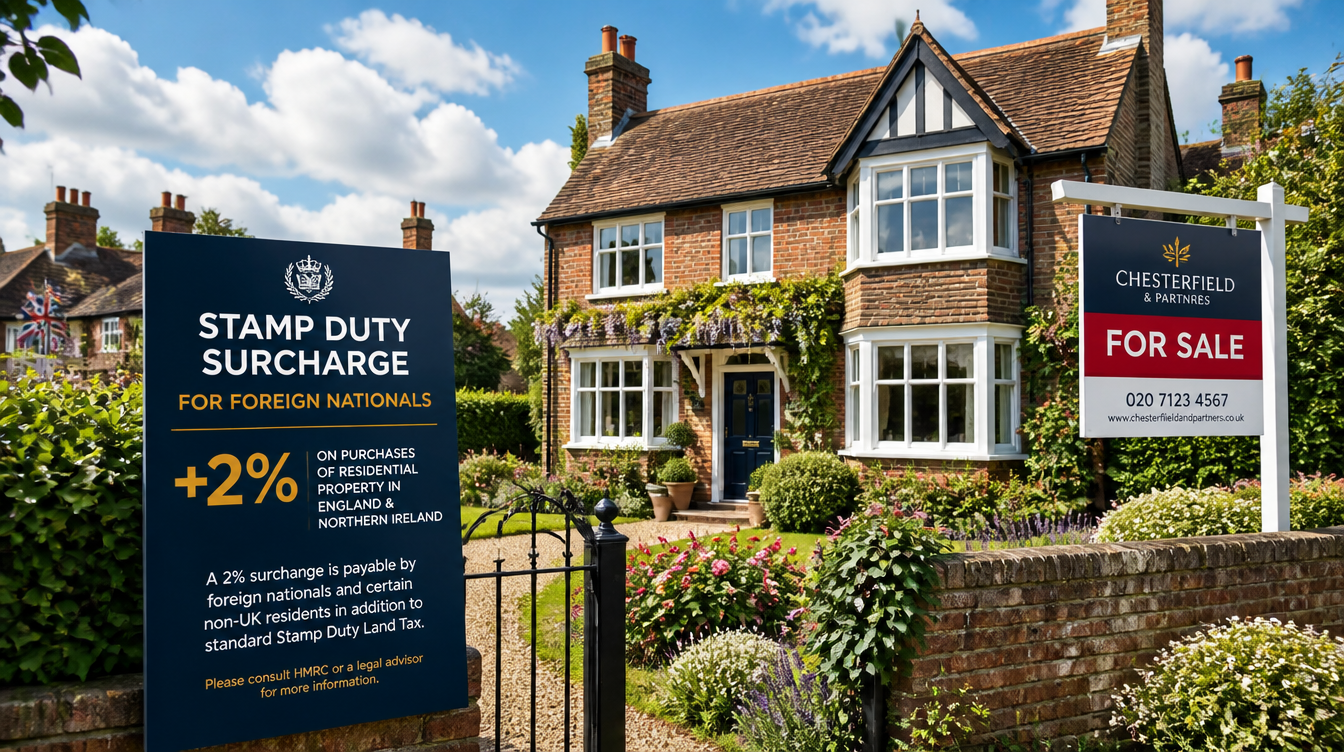
Understanding Stamp Duty in the UK
Stamp Duty Land Tax (SDLT) is a tax imposed on property purchases in the United Kingdom. It applies to both residential and non-residential properties, and the amount owed is determined by the purchase price of the property. The SDLT system is progressive, meaning that the rate of tax increases as the value of the property increases. For example, as of the latest regulations, the first £125,000 of a property purchase is tax-free, while purchases above this threshold incur increasing rates of tax.
To calculate the stamp duty due on a property, buyers must consider the purchase price and apply the relevant rates. The calculation is tiered, with different portions of the purchase price being taxed at different rates. For instance, if a property is purchased for £300,000, the first £125,000 is tax-free, the next £125,000 is taxed at 2%, and the remaining £50,000 is taxed at 5%. This results in a total stamp duty of £5,000 for that purchase. Buyers can use online calculators provided by the government or financial institutions to estimate their stamp duty liability accurately.
It is essential for potential buyers to understand that stamp duty is due upon completion of the property purchase, and failure to pay it can result in penalties. Additionally, there are various exemptions and reliefs available, such as for first-time buyers or for certain types of properties, which can significantly reduce the amount payable.
What is the Foreign National Stamp Duty?
The Foreign National Stamp Duty is a surcharge applied to property purchases made by foreign nationals in the UK. This surcharge was introduced to address concerns about the impact of foreign investment on the UK housing market, particularly in high-demand areas where property prices have escalated. The surcharge is currently set at 2% on top of the standard stamp duty rates applicable to all buyers.
Eligibility for the foreign national stamp duty surcharge is determined primarily by the residency status of the buyer. A foreign national is defined as someone who is not a UK resident for tax purposes. This means that individuals who have not been living in the UK for at least 183 days in the previous tax year may be subject to this surcharge when purchasing property. It is important for potential buyers to assess their residency status carefully, as this will directly affect their tax obligations.
In addition to the residency criteria, foreign nationals must also be aware of the broader implications of purchasing property in the UK. These can include additional legal requirements, potential restrictions on financing options, and the necessity of engaging with local legal and financial experts to navigate the complexities of the UK property market.
The Non-UK Resident Stamp Duty Explained
The non-UK resident stamp duty is specifically tailored for individuals who do not reside in the UK and are looking to invest in property. The primary distinction between UK residents and non-residents lies in the tax treatment of property purchases. Non-residents are subject to the additional 2% surcharge, which is not applicable to UK residents.
This difference can significantly impact the overall cost of purchasing property. For instance, a non-resident buying a property valued at £500,000 would incur a stamp duty of £15,000, which includes the standard rate of £13,000 plus the additional £2,000 surcharge. In contrast, a UK resident would only pay £13,000 in stamp duty for the same property.
The implications of this surcharge extend beyond the immediate financial impact. Non-UK residents may also face challenges in securing mortgages or financing options, as many lenders prefer to work with local buyers who have established credit histories in the UK. This can necessitate a more thorough due diligence process and may require foreign buyers to provide additional documentation to demonstrate their financial stability.
Furthermore, non-residents should be aware of the potential for changes in tax regulations that could affect their investments. Keeping abreast of the latest developments in property tax law is crucial for making informed purchasing decisions and ensuring compliance with UK tax obligations.
Overseas Buyer Surcharge: Key Details
The overseas buyer surcharge is an additional cost imposed on foreign nationals purchasing property in the UK. As mentioned earlier, this surcharge is currently set at 2% of the purchase price, which is applied on top of the standard stamp duty rates. This means that the total stamp duty liability for foreign buyers can be significantly higher than for UK residents.
To illustrate how the surcharge applies, consider a foreign national purchasing a property for £750,000. The stamp duty calculation would be as follows:
- First £125,000: 0% = £0
- Next £125,000: 2% = £2,500
- Next £250,000: 5% = £12,500
- Next £250,000: 10% = £25,000
- Overseas buyer surcharge (2%): £750,000 x 2% = £15,000
This results in a total stamp duty liability of £55,000 for the foreign buyer, compared to £40,000 for a UK resident purchasing the same property.
It is essential for overseas buyers to factor this surcharge into their overall budget when considering property purchases in the UK. Additionally, they should consult with tax advisors or legal experts to explore any potential exemptions or reliefs that may apply to their specific circumstances.
International SDLT UK: What You Should Know
International SDLT refers to the application of Stamp Duty Land Tax for buyers who are not residents of the UK. This includes foreign nationals and overseas investors who are looking to purchase property in the UK. Understanding the nuances of SDLT for international buyers is crucial, as it can differ significantly from the experience of UK residents.
One common misconception is that international buyers are exempt from SDLT. In reality, they are subject to the same rules as UK residents, with the added burden of the overseas buyer surcharge. This can create a perception that foreign investment is discouraged, but it is essential to recognize that the UK remains an attractive market for international buyers due to its stable economy and potential for capital appreciation.
Another misconception is that the SDLT process is overly complicated for international buyers. While there are additional considerations, such as residency status and potential financing challenges, many financial institutions and legal firms specialize in assisting foreign nationals with property transactions. These professionals can provide valuable guidance throughout the buying process, ensuring compliance with all legal requirements and helping to navigate the complexities of the UK property market.
How to Calculate Your Stamp Duty as a Foreign National
Calculating stamp duty as a foreign national involves a few straightforward steps. Here’s a step-by-step guide to help you determine your stamp duty liability:
- Determine the Purchase Price: Identify the total cost of the property you intend to purchase.
- Check the Standard SDLT Rates: Refer to the current SDLT rates applicable to property purchases in the UK.
- Calculate the Standard SDLT: Apply the standard rates to the relevant portions of the purchase price. Use the tiered structure to calculate the SDLT based on the thresholds.
- Add the Overseas Buyer Surcharge: If you are a foreign national, calculate the additional 2% surcharge on the entire purchase price.
- Sum Up the Total Stamp Duty: Combine the standard SDLT and the surcharge to arrive at your total stamp duty liability.
For convenience, various online calculators are available to assist in estimating your stamp duty. These tools can simplify the process, allowing you to input your purchase price and receive an instant calculation of your potential stamp duty liability.
Additionally, consulting with a tax advisor or property solicitor can provide clarity on your specific situation, ensuring you account for any potential exemptions or reliefs that may apply to your purchase.
Implications of the Stamp Duty Surcharge
The stamp duty surcharge for foreign nationals has significant implications for the UK property market. By increasing the cost of purchasing property for overseas buyers, the surcharge can deter some foreign investment, particularly in high-demand areas. This could lead to a cooling effect on property prices, especially in urban centers where foreign buyers are more prevalent.
For potential buyers, understanding the financial implications of the surcharge is crucial. It can affect not only the immediate cost of purchasing but also the long-term investment potential of the property. Buyers should consider the overall market trends and how changes in foreign investment might influence property values in the future.
Advice for potential buyers includes conducting thorough market research and seeking professional guidance. Engaging with local real estate experts can provide insights into market conditions and help identify properties that offer good value despite the additional costs associated with the surcharge. Additionally, potential buyers should explore financing options that may be available to them, as some lenders may have specific products tailored for foreign nationals.
Navigating the Buying Process as a Foreign National
Navigating the UK property buying process as a foreign national involves several legal considerations and potential challenges. Firstly, it is essential to understand the legal framework governing property purchases in the UK, including the necessity of engaging a solicitor to handle the transaction. A solicitor will ensure that all legal requirements are met, including conducting property searches and ensuring compliance with local regulations.
Financing options for foreign buyers can also differ from those available to UK residents. Many lenders may require a larger deposit from foreign nationals, often ranging from 25% to 40% of the property value. Additionally, foreign buyers may face stricter lending criteria, including the need to provide proof of income and financial stability, which can complicate the mortgage application process.
It is advisable for foreign nationals to prepare all necessary documentation in advance. This may include proof of identity, financial statements, tax information, and any other relevant documentation that lenders or solicitors may require. Engaging with a mortgage broker who specializes in foreign national transactions can also facilitate the process, helping buyers find suitable financing options tailored to their needs.
Frequently Asked Questions
What is the current rate for foreign national stamp duty in the UK?
The surcharge is currently set at 2% on top of standard rates.
Are there any exemptions for foreign nationals regarding stamp duty?
Certain exemptions may apply, such as for first-time buyers.
How does the stamp duty surcharge affect property investment?
It increases the overall cost of purchasing property in the UK.
Can foreign nationals reclaim stamp duty if they sell the property?
Generally, stamp duty is not refundable upon selling.
What documentation is required for foreign nationals to buy UK property?
Proof of identity, financial statements, and tax information may be needed.
