

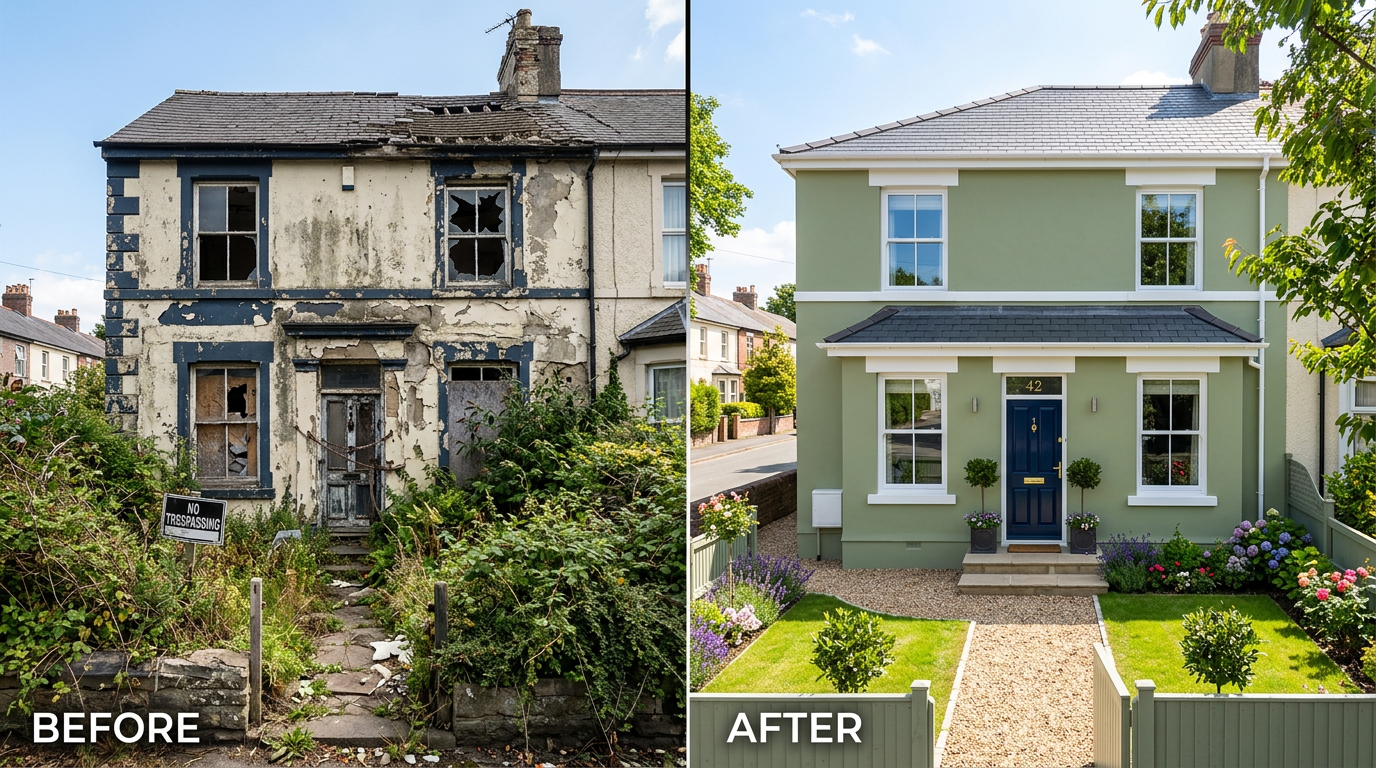
Understanding Empty Property Refurbishment Bridging Loans
Refurbishment bridging loans are short-term financing solutions specifically designed to facilitate renovation projects on properties that are currently unoccupied or derelict. These loans enable property investors and developers to acquire and refurbish properties quickly, often before securing more permanent financing options. The primary purpose of an empty property refurbishment bridging loan is to provide immediate access to capital that can be used for essential repairs, upgrades, or complete renovations. This type of loan is particularly beneficial for properties that require significant work before they can be rented or sold.
How these loans work is straightforward. Once a borrower identifies a suitable empty or derelict property, they can apply for a bridging loan to cover the purchase price and refurbishment costs. The loan is typically secured against the property itself, allowing lenders to assess the potential value after refurbishment when determining the loan amount. This approach contrasts with traditional mortgages, which often require a property to be in good condition before financing is approved.
Bridging loans for empty properties are characterized by their speed and flexibility. Unlike conventional loans that can take weeks or even months to process, bridging loans can often be approved within days. This rapid turnaround is crucial for investors looking to capitalize on opportunities in the property market, particularly in competitive scenarios such as auctions or distressed sales. Additionally, these loans can be tailored to the specific needs of the borrower, allowing for customized repayment terms based on the expected timeline for the refurbishment project.
In summary, empty property refurbishment bridging loans serve as a vital financial tool for property investors and developers aiming to revitalize neglected properties. By providing quick access to funds, these loans enable borrowers to undertake significant renovations, ultimately enhancing the property’s value and marketability.
Why Choose a Bridging Loan for Derelict Properties?
Choosing a bridging loan for derelict properties comes with several advantages that make it an appealing option for property investors. One of the primary benefits is the speed at which these loans can be secured. Traditional financing options often involve lengthy application processes, requiring extensive documentation and credit checks, which can delay renovation plans. In contrast, bridging loans can be processed quickly, allowing investors to move swiftly on opportunities that may otherwise be lost.
Another significant benefit is the flexibility that bridging loans offer. Lenders typically focus on the potential value of the property post-refurbishment rather than the current condition. This means that even properties in poor condition can qualify for financing, provided the borrower has a solid renovation plan in place. This flexibility is particularly advantageous for investors looking to purchase derelict houses that require extensive work before they can be occupied or sold.
Bridging loans also provide an opportunity for leveraging existing equity. Investors can use the equity from other properties to secure a bridging loan, which can be particularly useful when financing renovations on multiple properties simultaneously. This strategy allows investors to expand their portfolios without tying up significant amounts of cash in each project.
Moreover, the interest rates on bridging loans, while generally higher than traditional mortgages, can be justified by the speed and convenience they offer. Investors can often recoup these costs through the increased value of the property post-renovation. The ability to quickly renovate and either sell or rent out the property can lead to a faster return on investment, making bridging loans a viable option for those looking to capitalize on the property market.
In summary, bridging loans for derelict properties provide speed, flexibility, and the potential for leveraging equity, making them an attractive financing option for property investors. The ability to act quickly on renovation opportunities can significantly enhance an investor’s portfolio and overall profitability.
Eligibility Criteria for Empty Home Renovation Loans in the UK
Obtaining an empty home renovation loan in the UK involves meeting specific eligibility criteria set by lenders. Understanding these requirements is crucial for potential borrowers to ensure a smooth application process. Generally, lenders will assess several factors when considering an application for an empty property refurbishment bridging loan.
First and foremost, the condition of the property plays a significant role in the eligibility assessment. Lenders will typically require a valuation of the property to determine its current market value and potential value post-renovation. Properties that are severely dilapidated may require a more detailed inspection to assess the extent of necessary repairs.
Another critical factor is the borrower’s financial standing. Lenders will evaluate the applicant’s credit history, income, and existing debts to gauge their ability to repay the loan. While bridging loans are often more lenient than traditional mortgages regarding credit scores, having a solid financial background can improve the chances of approval and potentially secure better interest rates.
Additionally, a well-structured renovation plan is essential. Borrowers should provide detailed documentation outlining the intended renovations, estimated costs, and a timeline for completion. This plan demonstrates to lenders that the borrower has a clear strategy for increasing the property’s value, which is crucial for securing the loan.
Finally, the loan-to-value (LTV) ratio is a vital consideration. Lenders typically offer a percentage of the property’s value as a loan, and this ratio can vary based on the property’s condition and the borrower’s financial profile. Understanding the maximum LTV that a lender is willing to offer can help borrowers gauge how much they can borrow for their renovation projects.
In conclusion, the eligibility criteria for empty home renovation loans in the UK focus on the property’s condition, the borrower’s financial standing, the quality of the renovation plan, and the loan-to-value ratio. By preparing adequately and understanding these requirements, potential borrowers can enhance their chances of securing the necessary funding for their refurbishment projects.
The Process of Securing a Bridging Loan for Vacant Property Refurb
Securing a bridging loan for a vacant property refurbishment involves several key steps that borrowers must follow to ensure a successful application. Understanding this process can help streamline the experience and increase the likelihood of approval.
- Assess Your Financial Needs: Begin by determining how much funding you require for both the purchase of the property and the planned renovations. Having a clear budget will guide your loan application and help you identify suitable lenders.
- Research Lenders: Not all lenders offer the same terms and conditions for bridging loans. It’s essential to research various lenders to find one that specializes in refurbishment bridging loans. Consider factors such as interest rates, fees, and the speed of processing applications.
- Prepare Documentation: Gather all necessary documentation for your application. This typically includes proof of identity, financial statements, details of the property, and a comprehensive renovation plan. The more detailed your plan, the better your chances of approval.
- Apply for the Loan: Once you have your documentation in order, submit your application to the chosen lender. Be prepared to answer questions about your financial situation and the proposed renovations.
- Property Valuation: After submitting your application, the lender will conduct a valuation of the property. This step is crucial as it helps determine the loan amount you may be eligible for based on the property’s current and potential value.
- Loan Approval: If your application is approved, the lender will issue a loan offer detailing the terms and conditions. Review these carefully and ensure they align with your expectations before accepting.
- Drawdown of Funds: Upon acceptance of the loan offer, the funds will be released, allowing you to proceed with the purchase and renovation of the property. Ensure you have a clear plan for utilizing these funds efficiently.
- Renovation and Repayment: As you complete the renovations, keep track of expenses and timelines. Once the project is finished, you can either sell the property, refinance into a long-term mortgage, or rent it out, depending on your investment strategy.
In summary, securing a bridging loan for vacant property refurbishment involves assessing financial needs, researching lenders, preparing documentation, applying for the loan, undergoing property valuation, receiving loan approval, drawing down funds, and managing renovation and repayment. By following these steps, borrowers can navigate the process more effectively and achieve their property investment goals.
Cost Considerations for Refurbishment Bridging Loans
When considering refurbishment bridging loans, understanding the associated costs is crucial for effective budgeting and financial planning. These loans can be a powerful tool for property investors, but they come with various fees and interest rates that must be accounted for.
Typically, the costs associated with refurbishment bridging loans include:
- Interest Rates: Bridging loans usually have higher interest rates compared to traditional mortgages. Rates can vary significantly based on the lender, the borrower’s creditworthiness, and the property’s condition. It’s essential to compare offers from different lenders to find the most competitive rate.
- Arrangement Fees: Most lenders charge an arrangement fee for processing the loan application. This fee can range from 1% to 2% of the loan amount and is often deducted from the total funds released.
- Valuation Fees: A property valuation is a standard requirement for securing a bridging loan. Borrowers should expect to pay for this service, which can vary based on the property’s location and complexity.
- Legal Fees: Engaging a solicitor or conveyancer to handle the legal aspects of the loan and property purchase is advisable. Legal fees can vary widely, so it’s wise to obtain quotes from several professionals.
- Exit Fees: Some lenders charge an exit fee when the loan is repaid. This fee can also be a percentage of the loan amount and should be factored into the overall cost of borrowing.
- Renovation Costs: Beyond the loan costs, borrowers must budget for the actual renovation work. This includes materials, labor, permits, and any unforeseen expenses that may arise during the project.
Budgeting for these costs is essential to ensure that the refurbishment project remains financially viable. A well-prepared budget will help you avoid unexpected financial strain and ensure that you can complete the renovations as planned. Additionally, it’s advisable to set aside a contingency fund to cover any unexpected expenses that may arise during the refurbishment process.
In conclusion, understanding the cost considerations for refurbishment bridging loans is vital for effective financial planning. By accounting for interest rates, fees, and renovation costs, borrowers can make informed decisions and maximize their investment potential.
Case Studies: Successful Renovations with Bridging Loans
Examining real-life examples of successful renovations funded by bridging loans can provide valuable insights into the potential of this financing option. Here are a few case studies that highlight how property investors have effectively utilized refurbishment bridging loans to transform empty and derelict properties.
Case Study 1: Transforming a Derelict House into a Family Home
A property investor purchased a derelict house in a desirable neighborhood for £200,000. The property required extensive renovations, including structural repairs, new plumbing, and modernizing the interior. The investor secured a bridging loan of £250,000, which covered the purchase price and an estimated £50,000 for renovations. Within six months, the renovations were completed, and the property was valued at £350,000. The investor sold the property, repaying the bridging loan and realizing a profit of £100,000.
Case Study 2: Converting a Vacant Commercial Property into Residential Units
Another investor identified a vacant commercial property that had been unused for several years. The property was purchased for £300,000, and the investor secured a bridging loan of £400,000 to cover the purchase and conversion costs into residential units. The renovation involved significant structural changes and compliance with residential building codes. After a year of renovations, the property was fully leased, generating a monthly income of £4,000. The investor later refinanced the bridging loan into a long-term mortgage, benefiting from the increased property value and rental income.
Case Study 3: Flipping a Distressed Property
A seasoned property flipper acquired a distressed property at auction for £150,000. With a bridging loan of £200,000, the investor planned to renovate the property quickly and sell it for a profit. The renovations focused on cosmetic upgrades, including new flooring, kitchen, and bathroom remodels. Within three months, the property was listed and sold for £250,000. The investor repaid the bridging loan and pocketed a profit of £50,000, demonstrating the effectiveness of quick renovations funded by bridging finance.
These case studies illustrate the potential of refurbishment bridging loans to facilitate successful property renovations. By leveraging this type of financing, investors can transform derelict properties into valuable assets, generating significant returns on their investments. The key takeaway from these examples is the importance of having a clear renovation plan, understanding the costs involved, and being prepared to manage the project effectively.
Common Challenges and How to Overcome Them
While refurbishment bridging loans offer numerous advantages, they also come with potential challenges that borrowers should be aware of. Understanding these challenges and having strategies to mitigate them can help ensure a successful renovation project.
One common challenge is the risk of underestimating renovation costs. Many investors may overlook hidden issues within a property, leading to budget overruns. To overcome this, it’s essential to conduct thorough inspections and obtain multiple quotes from contractors before finalizing a renovation budget. Setting aside a contingency fund of at least 10-15% of the total renovation costs can also provide a buffer for unexpected expenses.
Another challenge is the pressure of tight timelines. Bridging loans are typically short-term, which means that borrowers must complete renovations quickly to avoid additional interest costs. To manage this, create a detailed project timeline and set realistic milestones. Hiring experienced contractors who can deliver quality work on time is also crucial for staying on schedule.
Additionally, borrowers may face difficulties in securing a quick exit strategy to repay the bridging loan. Whether through selling the property or refinancing into a long-term mortgage, having a clear exit plan is vital. Before taking out a bridging loan, assess the local property market and have a strategy in place for how you will repay the loan once renovations are complete.
Finally, borrowers should be aware of the potential for fluctuating property values. Market conditions can change, impacting the resale value of the renovated property. To mitigate this risk, conduct thorough market research and consider consulting with real estate professionals to understand current trends and pricing in the area.
In conclusion, while there are challenges associated with refurbishment bridging loans, being proactive and prepared can help borrowers navigate these obstacles successfully. By conducting thorough research, setting realistic budgets and timelines, and having clear exit strategies, investors can maximize the benefits of bridging finance for their renovation projects.
Tips for Maximizing Your Investment in Refurbished Properties
Maximizing your investment in refurbished properties requires careful planning and strategic decision-making throughout the renovation process. Here are some best practices to consider that can enhance the value of your investment post-refurbishment.
- Focus on High-Impact Renovations: Prioritize renovations that significantly increase the property’s value. Kitchen and bathroom upgrades, energy-efficient improvements, and enhancing curb appeal are often the most impactful.
- Maintain Quality Standards: While it may be tempting to cut corners to save costs, maintaining high-quality standards in renovations can lead to better long-term returns. Quality work attracts higher-paying tenants or buyers and reduces future maintenance costs.
- Consider Local Market Trends: Stay informed about local property market trends and buyer preferences. Tailoring renovations to meet the demands of potential buyers or renters can enhance the property’s appeal and value.
- Utilize Professional Help: Engaging experienced contractors, architects, and real estate agents can provide valuable insights and expertise. Their knowledge can help you avoid costly mistakes and ensure the project is completed efficiently.
- Market the Property Effectively: Once renovations are complete, invest time and resources into marketing the property. High-quality photographs, virtual tours, and effective online listings can attract potential buyers or tenants quickly.
By implementing these tips, property investors can maximize their returns on refurbished properties. A well-planned renovation strategy that focuses on quality and market demand can significantly increase property value and profitability.
Conclusion: Making the Most of Bridging Loans for Empty Properties
Refurbishment bridging loans present a valuable opportunity for property investors looking to revitalize empty and derelict properties. By understanding the mechanics of these loans, the eligibility criteria, and the associated costs, investors can navigate the process effectively and make informed decisions.
Throughout this article, we have explored the benefits of using bridging loans, the steps to secure funding, and strategies for maximizing investment returns. From case studies illustrating successful renovations to tips for overcoming common challenges, it is clear that with careful planning and execution, refurbishment bridging loans can lead to significant financial gains.
For those considering entering the property market or expanding their investment portfolios, refurbishment bridging loans offer a fast and flexible financing solution. By leveraging these loans, investors can transform neglected properties into valuable assets, ultimately contributing to the revitalization of communities and enhancing their own financial success.
Frequently Asked Questions
What is an empty property refurbishment bridging loan?
A short-term loan designed to finance renovations on empty properties.
How quickly can I get a bridging loan for a derelict house?
Bridging loans can often be secured within a few days to weeks.
What are the typical interest rates for refurbishment bridging loans?
Interest rates vary but are generally higher than traditional mortgages.
Can I use a bridging loan for any type of property renovation?
Yes, as long as the property is empty or derelict and meets lender criteria.
What should I budget for when renovating a vacant property?
Consider costs for materials, labor, permits, and potential unexpected expenses.
