

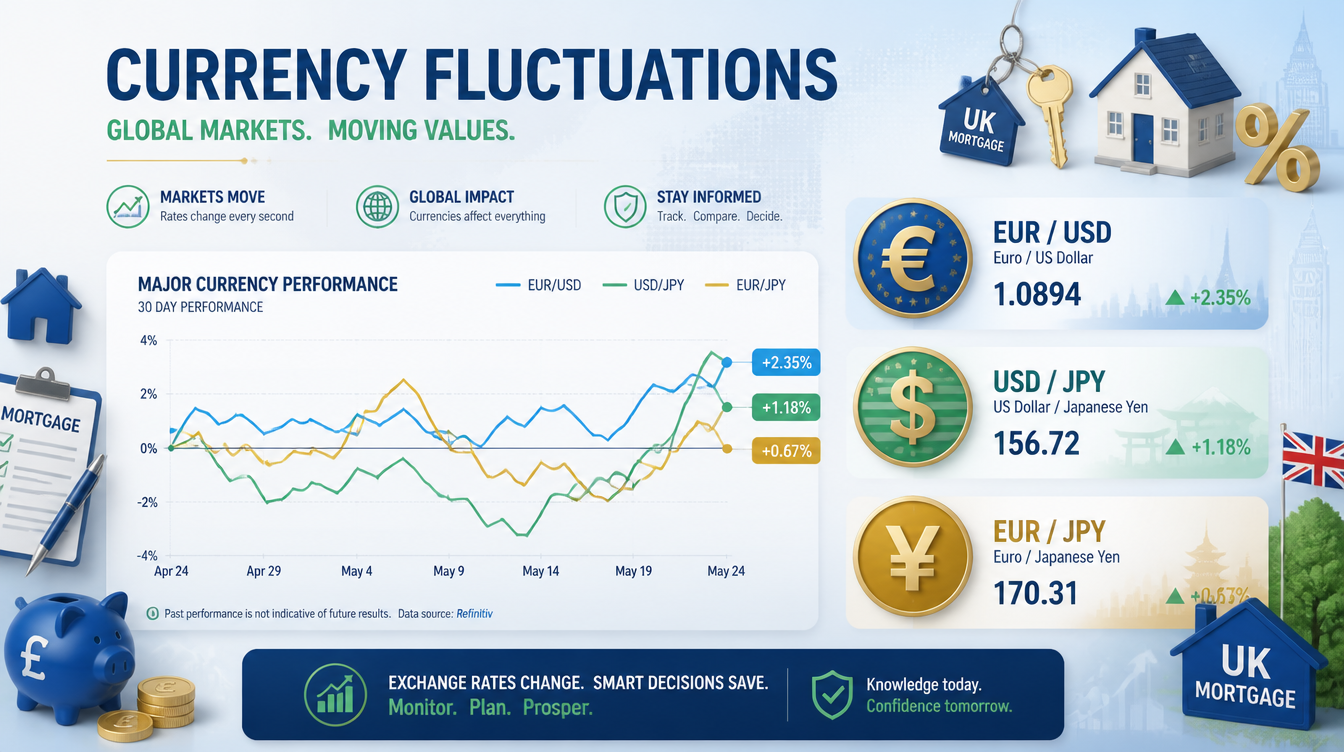
Understanding Currency Fluctuations
Currency fluctuations refer to the changes in the value of one currency relative to another over a specific period. These fluctuations can be caused by various factors, including economic indicators, interest rates, political stability, and market speculation. For instance, if the UK economy shows signs of growth, the British pound may strengthen against other currencies, making UK exports more expensive and imports cheaper. Conversely, political uncertainty, such as Brexit negotiations, can lead to a depreciation of the pound, affecting its value against other currencies.
Several key factors influence currency values:
- Interest Rates: Central banks, like the Bank of England, set interest rates that directly affect currency values. Higher interest rates offer lenders in an economy a higher return relative to other countries, attracting foreign capital and causing the currency to appreciate.
- Economic Indicators: Reports on GDP growth, employment rates, and inflation can influence investor perceptions of a country’s economic health, thereby impacting currency strength.
- Political Stability: Countries with less risk for political turmoil are more attractive to foreign investors, which can bolster currency value.
- Market Speculation: Traders’ perceptions and predictions about future events can lead to fluctuations. If traders believe a currency will strengthen, they will buy more of it, driving up its value.
Understanding these factors is crucial for UK homeowners with overseas mortgages, as currency fluctuations can significantly affect their repayment amounts.
The Impact of Currency Fluctuations on UK Mortgages
Currency fluctuations can have a profound impact on UK mortgage payments, particularly for those with mortgages denominated in foreign currencies. When the value of the pound falls against the currency in which the mortgage is denominated, the cost of repayments in pounds increases. For example, if a UK homeowner has a mortgage in euros and the pound weakens against the euro, they will need to pay more pounds to cover the same euro mortgage payment.
Consider a scenario where a UK homeowner has a €200,000 mortgage with a fixed monthly payment of €1,000. If the exchange rate is 1.2, the homeowner pays £833.33 per month. However, if the pound depreciates to an exchange rate of 1.5, the same €1,000 payment would now cost £666.67, significantly impacting the homeowner’s budget.
Real-life examples illustrate this impact vividly. During the Brexit referendum in 2016, the pound fell sharply against the euro and the dollar. Homeowners with overseas mortgages faced increased payments, leading to financial strain for many. Similarly, fluctuations during the COVID-19 pandemic saw the pound’s value fluctuate, causing uncertainty for those with foreign currency mortgages.
Understanding the implications of these fluctuations is essential for homeowners to manage their financial commitments effectively.
FX Risk in the UK Property Market
FX risk, or foreign exchange risk, refers to the potential financial loss that can occur due to changes in exchange rates. For UK property investors, particularly those purchasing overseas properties or taking out foreign currency mortgages, FX risk is a significant concern. This risk can lead to unexpected increases in mortgage payments, affecting overall investment returns.
For instance, a UK investor purchasing a property in Spain with a mortgage in euros faces FX risk. If the pound weakens against the euro after the mortgage is taken out, the investor will find their mortgage payments increasing in pound terms. This situation can lead to negative cash flow, especially if rental income does not increase correspondingly.
Moreover, FX risk can deter potential investors from entering the overseas property market. The fear of currency volatility may lead them to seek properties within the UK, where they feel more secure about their financial commitments. However, this can limit their investment opportunities and potential returns. On the other hand, savvy investors can use FX risk to their advantage by timing their purchases and leveraging currency movements to maximize their gains.
In summary, FX risk plays a crucial role in the UK property market, influencing investment decisions and financial outcomes for homeowners and investors alike.
Strategies to Mitigate Currency Risks
Mitigating currency risks is essential for UK homeowners with overseas mortgages. There are several strategies that can be employed to protect against the adverse effects of currency fluctuations:
- Hedging Options: Homeowners can utilize hedging strategies to protect against currency risk. This involves using financial instruments such as options or futures contracts to lock in exchange rates. For example, a homeowner can purchase a currency option that gives them the right to exchange currency at a predetermined rate, thus protecting them from unfavorable movements.
- Forward Contracts: A forward contract allows homeowners to set an exchange rate for a future date. This can be particularly useful for those expecting to make significant payments in the future. By locking in a rate today, they can avoid potential increases in their mortgage payments due to currency depreciation.
- Diversification: Investors can diversify their currency exposure by holding assets in different currencies. This strategy can help spread the risk and reduce the impact of adverse currency movements on their overall portfolio.
- Regular Monitoring: Keeping an eye on currency trends and economic indicators can help homeowners make informed decisions about their mortgage payments. By staying informed, they can take proactive steps to mitigate risks, such as adjusting payment strategies when favorable exchange rates arise.
Implementing these strategies requires careful planning and consideration of individual financial situations. Consulting with financial experts can provide valuable insights and help homeowners navigate the complexities of currency risk management.
Choosing the Right Currency Mortgage
When considering a mortgage for overseas property, understanding the types of currency mortgages available is crucial. Each type comes with its own benefits and drawbacks:
- Fixed-Rate Mortgages: These mortgages offer stability as the interest rate remains constant throughout the loan term. This predictability can be beneficial for budgeting, but it may not be advantageous if interest rates fall.
- Variable-Rate Mortgages: These mortgages fluctuate with market interest rates. While they can offer lower initial payments, there is a risk of increased costs if rates rise. Homeowners should assess their risk tolerance before choosing this option.
- Currency-Specific Mortgages: Some lenders offer mortgages specifically denominated in foreign currencies. These can be advantageous for homeowners earning income in the same currency, as they can avoid FX risk. However, they also expose borrowers to the risks associated with currency fluctuations.
Each mortgage type has its unique implications for repayments and risk exposure. Homeowners should carefully evaluate their financial situation, currency exposure, and long-term goals when selecting the right mortgage type. Consulting with a mortgage broker can provide tailored advice and help navigate the complexities of currency mortgages.
Case Studies: Currency Fluctuations and Mortgage Payments
Analyzing past currency trends can provide valuable insights into the impact of currency fluctuations on mortgage payments. One notable case is that of a UK homeowner who purchased a property in France in 2015. At the time, the exchange rate was approximately 1.4 euros to the pound. The homeowner secured a €300,000 mortgage, resulting in monthly payments of around £2,142.
However, by 2018, the pound had depreciated to 1.1 euros to the pound. This change meant that the same €2,000 payment now cost the homeowner £1,818, a significant increase in their repayment burden. This case illustrates how currency fluctuations can dramatically alter the financial landscape for homeowners with foreign currency mortgages.
Another example involves a UK investor who purchased a buy-to-let property in Australia. Initially, the exchange rate was favorable, allowing for lower mortgage payments. However, as the Australian dollar strengthened against the pound, the investor found themselves facing increased costs. The investor’s rental income did not keep pace with the rising mortgage payments, leading to cash flow issues.
These case studies highlight the importance of understanding currency trends and their potential impact on mortgage payments. Homeowners must remain vigilant and consider the implications of currency fluctuations when managing their overseas mortgages.
Future Trends in Currency and Mortgage Payments
As global economic conditions evolve, so too will currency movements and their impact on mortgage payments. Analysts predict that economic recovery from the COVID-19 pandemic will lead to fluctuations in currency values as countries adjust their monetary policies. For instance, if the Bank of England raises interest rates to combat inflation, the pound may strengthen against other currencies, benefiting UK homeowners with foreign currency mortgages.
Conversely, geopolitical tensions, such as trade disputes or political instability, can lead to currency depreciation, increasing the cost of overseas mortgage payments. Homeowners should stay informed about economic indicators and global events that could influence currency movements.
Additionally, advancements in technology and financial services may provide new tools for homeowners to manage currency risk. Innovative financial products, such as automated hedging solutions, could become more accessible, allowing homeowners to protect against adverse currency movements more effectively.
In conclusion, understanding future currency trends is vital for homeowners with overseas mortgages. By staying informed and adapting strategies accordingly, they can navigate the complexities of currency fluctuations and manage their mortgage payments effectively.
Conclusion: Navigating Currency Fluctuations
Currency fluctuations can significantly impact overseas UK mortgage payments, leading to increased financial strain for homeowners. Understanding the factors influencing currency values, the implications of FX risk, and the strategies to mitigate these risks is essential for effective financial management.
Homeowners should carefully consider their mortgage options, stay informed about currency trends, and employ risk management strategies to navigate the complexities of currency fluctuations. By doing so, they can protect their investments and ensure financial stability in an ever-changing economic landscape.
Frequently Asked Questions
How do currency fluctuations affect my mortgage payments?
Currency fluctuations can increase or decrease the amount you owe in your local currency, impacting your overall mortgage payments.
What is FX risk in the context of UK property?
FX risk refers to the potential loss due to changes in exchange rates affecting property investments, particularly for those with foreign currency mortgages.
Can I hedge against currency fluctuations?
Yes, options like forward contracts can help lock in exchange rates for future payments, providing a safeguard against adverse currency movements.
What types of currency mortgages are available?
There are fixed-rate, variable-rate, and currency-specific mortgages tailored to different needs, each with its own benefits and drawbacks.
How can I prepare for future currency trends?
Stay informed on economic indicators and consider consulting with financial experts to navigate potential currency fluctuations effectively.
