

Understanding Bridging Loans
A bridging loan is a short-term financing option designed to provide immediate funds for property purchases or renovations. Typically used in scenarios where quick access to capital is necessary, bridging loans can be secured against residential or commercial properties. They are often employed by property investors, developers, or homeowners who need to act swiftly in a competitive market.
Common uses of bridging loans include purchasing properties at auction, funding renovations before a sale, or facilitating chain breaks in property transactions. For instance, if a buyer is looking to purchase a new home but is waiting for their current property to sell, a bridging loan can provide the necessary funds to complete the purchase without delay. This flexibility makes bridging loans an attractive option for those needing quick access to cash.
One of the primary advantages of bridging loans is their speed. Unlike traditional mortgages, which can take weeks or even months to process, bridging loans can often be approved and funded within days. This quick turnaround is crucial for buyers needing to secure a property quickly. Additionally, bridging loans can be tailored to meet specific needs, allowing for customized repayment terms and conditions. They also offer a higher loan-to-value (LTV) ratio compared to conventional financing options, making them accessible to a broader range of borrowers.
However, it is essential to consider the associated costs, such as higher interest rates and fees, which can make bridging loans more expensive in the long run. Borrowers should ensure they have a clear exit strategy to repay the loan, whether through the sale of a property or refinancing into a longer-term solution.
What is Development Finance?
Development finance refers to funding specifically designed for property development projects. This type of finance is typically used by developers to cover the costs associated with acquiring land, construction, and other development-related expenses. Development finance can take various forms, including loans, equity investments, and mezzanine finance, depending on the project’s scale and complexity.
Key features of development finance include the ability to borrow larger sums of money over a more extended period, usually ranging from six months to several years. This financing option is tailored to the unique needs of property developers, providing funds at different stages of the development process, from land acquisition to completion. Moreover, development finance often includes flexible repayment structures, allowing developers to pay interest only during the construction phase before switching to full repayments once the project is completed and generating income.
When considering development finance, it is crucial to assess the project’s viability and potential return on investment. Developers should evaluate factors such as location, market demand, and construction costs to ensure the project is financially sound. Additionally, engaging with financial advisors or development finance specialists can provide valuable insights and help navigate the complexities of securing funding for development projects.
Bridging Loan vs Development Finance: Key Differences
When comparing bridging loans and development finance, several key differences emerge that can significantly impact a borrower’s decision-making process.
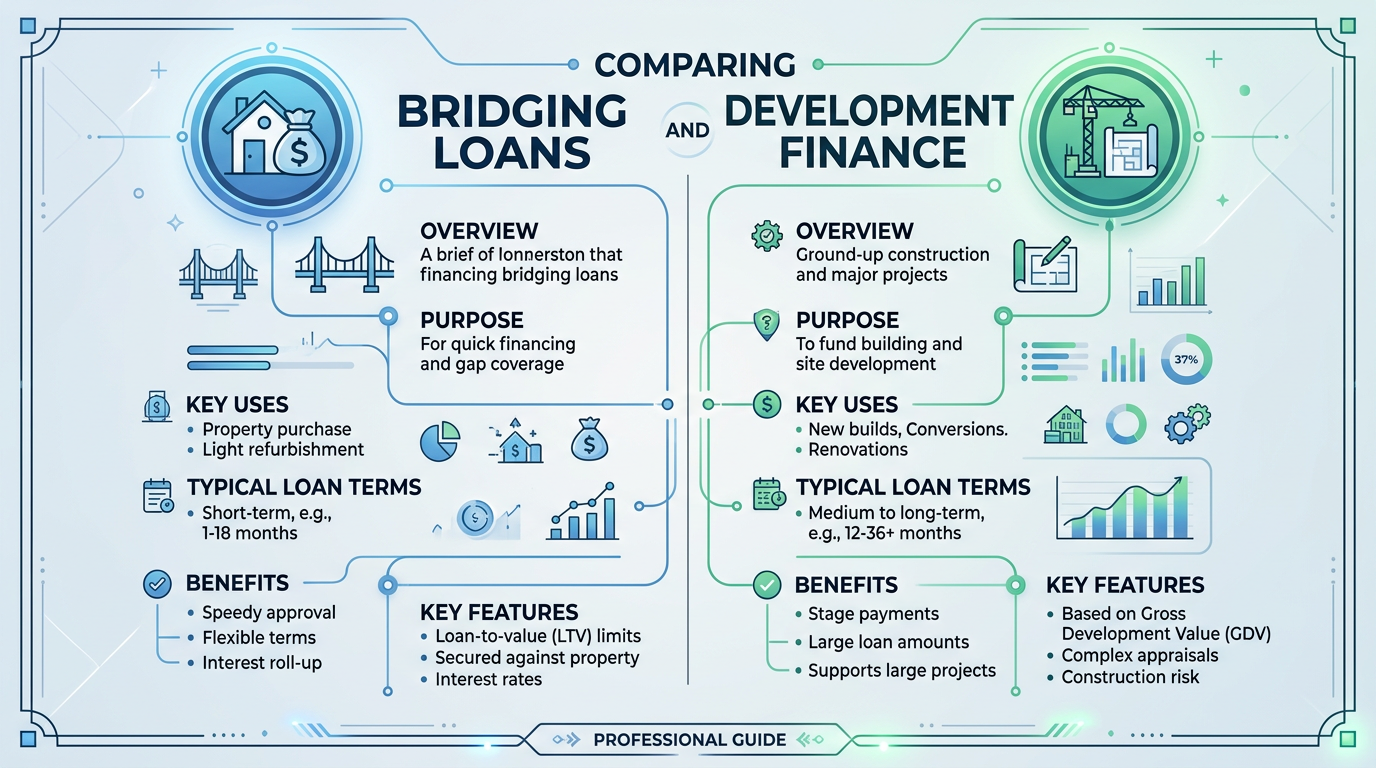
- Loan Terms: Bridging loans are typically short-term, lasting from a few weeks to a year, designed for immediate financial needs. In contrast, development finance is structured for longer-term projects, often spanning several months to years, depending on the development timeline.
- Interest Rates and Fees: Bridging loans generally come with higher interest rates, reflecting their short-term nature and the urgency of funding. Development finance, while also potentially costly, may offer lower rates due to the longer repayment periods and structured payment plans.
- Repayment Structures: Bridging loans usually require repayment in full at the end of the loan term, often necessitating a clear exit strategy. Development finance may allow for interest-only payments during the construction phase, with full repayments commencing once the project is completed and generating income.
Understanding these differences is crucial for borrowers to select the right financing option tailored to their specific needs. For instance, if a property investor needs quick access to funds for a time-sensitive purchase, a bridging loan may be the ideal choice. Conversely, if a developer is looking to finance a new build project over several years, development finance would be more appropriate.
Short-Term vs Development Loans: A Detailed Comparison
When evaluating short-term loans, such as bridging loans, against development loans, several factors come into play that can influence a borrower’s decision.
- Duration of Loans: Short-term loans, like bridging loans, are designed for quick access to funds, typically lasting from a few weeks to a year. In contrast, development loans are structured for longer durations, often spanning several months to years, allowing developers to manage projects effectively.
- Purpose and Flexibility: Bridging loans are primarily used for immediate funding needs, such as purchasing properties or covering temporary cash flow gaps. Development loans, however, are specifically tailored for property development, covering costs from land acquisition to construction and marketing. This specialization allows for greater flexibility in managing project timelines and funding requirements.
- Risk Factors Associated with Each: Bridging loans can pose significant risks if borrowers do not have a clear exit strategy, as failure to repay can lead to repossession of the property. Development loans carry their own risks, including potential project delays, cost overruns, and market fluctuations that can impact the project’s profitability. Developers should conduct thorough due diligence to mitigate these risks and ensure the project’s financial viability.
Ultimately, the choice between short-term loans and development loans hinges on the specific needs of the borrower and the nature of the project. For quick purchases or urgent financial needs, short-term loans may be the best fit. However, for comprehensive development projects requiring substantial funding over an extended period, development loans are likely the more suitable option.
Choosing the Right Option for Your Project
When faced with the decision between bridging loans and development finance, it is essential to assess your financial needs comprehensively. Start by evaluating the purpose of the funding: Are you looking to secure a property quickly, or are you planning a long-term development project? Understanding the specific requirements of your project will help narrow down the financing options available.
Next, consider your project timelines. If you need immediate access to funds to seize a time-sensitive opportunity, a bridging loan may be the right choice. Conversely, if your project involves multiple phases and requires sustained funding over time, development finance would be more appropriate.
Consulting with financial advisors or specialists in property finance can provide invaluable insights into the best financing route for your project. They can help you navigate the complexities of each option, assess your financial situation, and identify potential risks and rewards associated with bridging loans and development finance.
Finally, always have a clear exit strategy in place. Whether you plan to sell the property, refinance, or secure long-term financing, knowing how you will repay the loan is crucial to avoiding potential financial pitfalls.
Case Studies: Successful Uses of Bridging Loans and Development Finance
Examining real-life examples can provide valuable insights into the effective use of bridging loans and development finance.
For instance, a property investor may have used a bridging loan to purchase a residential property at auction. With the auction date approaching, they required immediate funding to secure the purchase. The bridging loan allowed them to complete the transaction quickly, and they subsequently renovated the property before selling it at a profit within a few months.
On the other hand, a developer may have utilized development finance to fund a new residential complex. The project involved acquiring land, obtaining planning permission, and constructing multiple units. By securing development finance, the developer could manage cash flow throughout the project, making interest-only payments during construction and transitioning to full repayments once the properties were sold or rented out.
These case studies highlight the versatility and effectiveness of both bridging loans and development finance in achieving property investment goals. Understanding the lessons learned from these examples can help borrowers make informed decisions about their financing options.
Frequently Asked Questions
What is the main difference between a bridging loan and development finance?
Bridging loans are short-term solutions, while development finance is for longer-term projects.
When should I use a bridging loan?
When you need quick access to funds for property purchases or renovations.
What are the typical interest rates for development finance?
Interest rates vary based on the project and lender, often higher than traditional loans.
Can I use a bridging loan for commercial properties?
Yes, bridging loans can be used for both residential and commercial properties.
How long does it take to secure a bridging loan?
Typically, bridging loans can be secured within a few days to a couple of weeks.
