

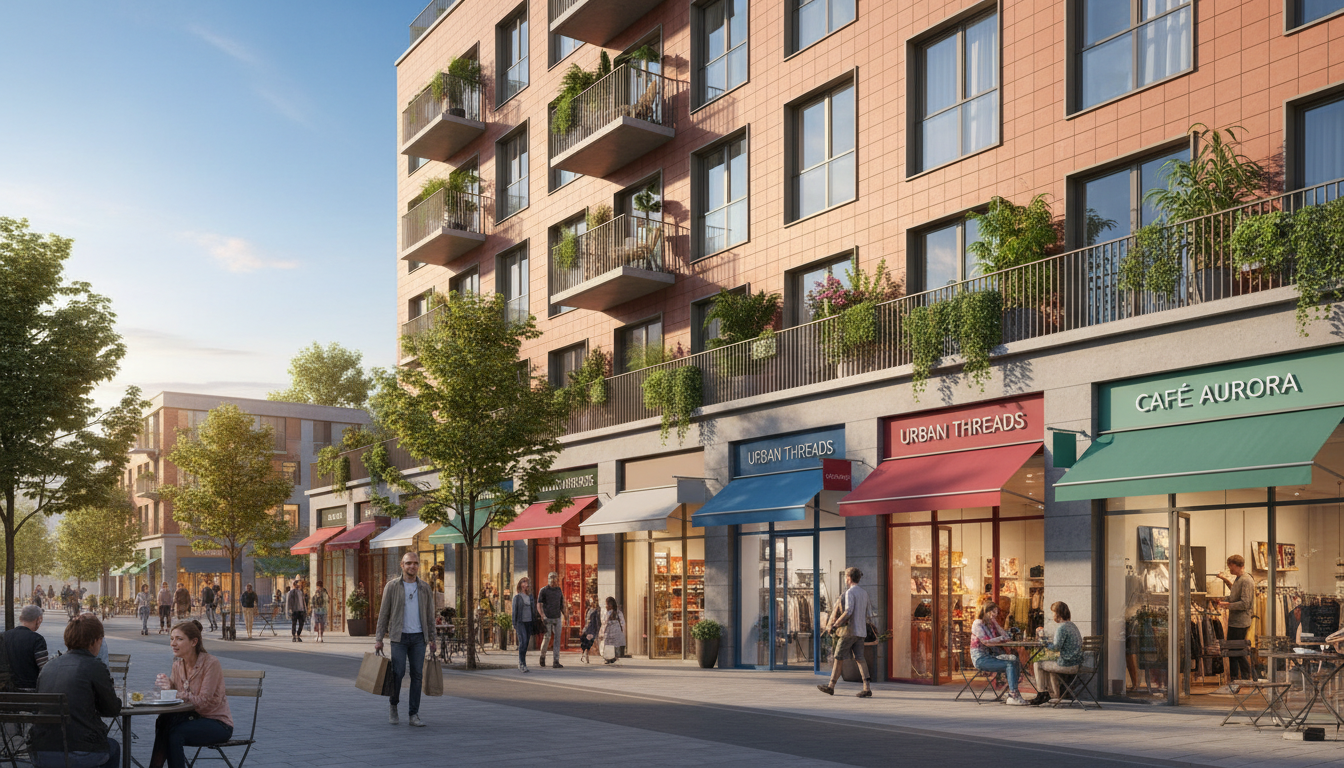
Buy-to-Let Mortgage for Property Above Commercial Premises
Buying a rental flat above a shop, office, restaurant, or other business premises can be attractive. These properties are often in busy town centres, close to transport links, and positioned where tenant demand may be strong. However, an above commercial BTL mortgage is not always as straightforward as a standard buy-to-let mortgage.
Lenders scrutinize the commercial unit below, considering factors such as the type of trade, building layout, entrance arrangement, resale demand, fire risk, noise, smells, lease terms, and the valuer’s comments. While some lenders are comfortable with a flat above low-risk commercial premises, others may decline the case before it reaches valuation.
At Lockwell Finance, we assist landlords and investors in structuring buy-to-let finance around the real risks of the property, not just the headline purchase price. If you are buying or refinancing a flat above commercial premises, send us the property details, and we will help you understand the most realistic route before you commit too far.
What Is an Above Commercial BTL Mortgage?
An above commercial BTL mortgage is a buy-to-let mortgage used to purchase or refinance a residential rental property located above, next to, or within the same building as commercial premises. Common examples include:
- A flat above a retail shop
- A maisonette above an office
- A residential unit above a café
- A flat above a pharmacy or convenience store
- A property above a restaurant, bar, takeaway, or salon
- A residential flat within a mixed-use building
- A converted upper floor above a commercial unit
While the property may still be residential from the tenant’s perspective, lenders assess it as a higher-risk security because the commercial premises can affect marketability, tenant appeal, insurance, fire safety, and long-term resale value.
Why Flats Above Shops Can Be Harder to Mortgage
A flat above a shop mortgage is more specialist because lenders want to know whether the property would still be easy to rent, easy to sell, and acceptable as security if the borrower defaults. The main concern is not simply that a business exists below the flat; it’s about the type of business, how it operates, and whether it creates a risk that could reduce the property’s value or tenant demand.
For example, a flat above a quiet accountancy office will usually be viewed differently from a flat above a late-night takeaway. A property above a pharmacy may be more acceptable than one above a bar with late opening hours. Similarly, a unit above a small convenience shop may be easier to finance than one above a restaurant with cooking extraction, odour, noise, and fire risk.
Lenders Usually Focus on Five Questions
- What is the commercial use below? Is it a shop, office, restaurant, café, takeaway, bar, salon, betting shop, or something else?
- Does the commercial unit create nuisance risk? Noise, smells, deliveries, waste storage, customers gathering outside, and late-night opening can all affect suitability.
- Is the property easy to resell? Lenders want confidence that there would be enough buyer demand if the property had to be sold.
- Is the flat independently accessible? Separate residential access is often important. Access through or across commercial space can cause problems.
- What does the valuer say? Even where a lender is open to the case, the valuation report can still make or break the application.
Are Buy-to-Let Mortgages Available for Flats Above Commercial Premises?
Yes, it can be possible to get a buy-to-let mortgage on a property above commercial premises, but lender choice is narrower than for a standard house or flat. Some lenders accept certain properties above or near commercial premises if the valuer confirms there is reliable demand and the commercial element is acceptable. Others restrict this type of property or only consider it on a case-by-case basis.
The right lender depends on the details of the property, including:
- The business type below
- Opening hours
- Leasehold or freehold structure
- Separate entrance and access
- Floor level
- Building height and layout
- Property condition
- Fire safety and escape routes
- Local tenant demand
- Comparable sales evidence
- Rental income and stress-test position
- Borrower profile
- Whether the purchase is personal or through an SPV limited company
If you are considering this type of property, it is advisable to check finance options before making an offer or paying for legal work. A property may look attractive on yield, but if only a small pool of lenders will consider it, the deposit, rate, and valuation risk may change the deal.
Planning to buy a flat above a shop or commercial unit? Request a free consultation with Lockwell Finance before you commit. We can help you understand whether the deal is likely to fit buy-to-let criteria or whether a specialist route may be needed.
Above Commercial BTL Mortgage vs Mixed Use BTL
The phrase “above commercial BTL mortgage” is often used for a residential flat above commercial premises. However, this is not always the same as a mixed-use BTL or semi-commercial mortgage.
Above Commercial BTL Mortgage
This usually applies where you are buying or refinancing the residential flat only. For example, you are purchasing the leasehold flat above a shop, but you are not buying the shop itself. In this case, the mortgage may still be a residential buy-to-let mortgage, provided the security is the residential unit only and the lender accepts the commercial proximity.
Mixed Use BTL or Semi-Commercial Mortgage
This may apply where you are buying the whole building, such as a shop on the ground floor with one or more flats above. In this case, the property includes both commercial and residential elements. A standard buy-to-let lender may not be suitable because the security includes commercial income, commercial leases, and business-use risk. A semi-commercial or commercial investment mortgage may be more appropriate.
Simple Example
A landlord buying a leasehold flat above a pharmacy may need an above commercial BTL mortgage. Conversely, a landlord buying the entire building with the pharmacy downstairs and two flats above may need a semi-commercial mortgage. That distinction matters because it affects lender type, valuation method, deposit expectations, pricing, underwriting, and legal checks.
Which Commercial Premises Are More Acceptable to Lenders?
Not every commercial unit is treated the same. Some uses are usually viewed as lower risk, while others can trigger more caution.
Usually More Acceptable
These may be easier to place, depending on the full case:
- Offices
- Pharmacies
- Small retail shops
- Estate agents
- Accountancy practices
- Professional services
- Daytime-only businesses
- Low-footfall commercial units
- Businesses without cooking, late hours, or heavy noise
More Case Dependent
These can still be possible, but lender appetite may vary:
- Cafés
- Hairdressers
- Beauty salons
- Convenience stores
- Launderettes
- Clinics
- Gyms
- Childcare premises
- Food-related businesses without late-night trading
Often More Difficult
These may reduce lender choice significantly:
- Hot food takeaways
- Restaurants with extraction systems
- Bars and pubs
- Nightclubs or late-night venues
- Betting shops
- Off-licences
- Businesses with late opening hours
- Premises with strong odours, waste, or delivery activity
- Commercial units with high fire, noise, or antisocial behaviour risk
A property above commercial premises is not automatically unmortgageable. The issue is whether the business below affects the flat’s suitability as rental security.
What Lenders Assess Before Approving an Above Commercial BTL Mortgage
The Commercial Occupier
Lenders will want to know what business operates below the flat. A low-risk, daytime retail unit is usually easier than a late-night food business. They may also consider whether the commercial unit could change use in the future. For example, a quiet shop today might become a takeaway later if the lease and planning position allow it. That future risk can affect the lender’s view.
The Valuer’s Comments
The valuer plays a major role. Even if a lender’s written criteria appear flexible, the final decision may depend on whether the valuer confirms the property is suitable security. The valuer may comment on:
- Demand for similar properties in the local area
- Whether the commercial element affects saleability
- Noise, smell, or nuisance risk
- Fire safety or access concerns
- Comparable sales evidence
- Rental demand
- Whether the property is suitable for lending
A down valuation or adverse valuer comment can reduce the maximum loan, force a larger deposit, or lead to a decline.
Separate Access
Separate access is often important. A flat with its own front door or independent residential entrance is usually stronger than one accessed through the shop, across a service yard, or via a narrow alley shared with commercial waste bins. Good access helps with:
- Tenant appeal
- Security
- Fire escape
- Privacy
- Long-term marketability
- Surveyor confidence
Noise and Smell
Noise and odour are common reasons lenders become cautious. A restaurant, takeaway, or bar can affect the tenant’s enjoyment of the property and reduce resale demand. Even where the current tenant is happy, lenders think about the property’s marketability over the full mortgage term.
Fire Safety and Escape Routes
Properties above commercial premises can raise questions around fire separation, escape routes, alarms, and building safety. This is especially relevant where the commercial unit involves cooking, gas, electrical equipment, flammable materials, or late-night use. Landlords must also meet their own rental property safety responsibilities. For a buy-to-let property, safety compliance is not just a legal issue; it can also affect insurance, letting suitability, and lender confidence.
Leasehold Structure
Many flats above commercial premises are leasehold. Lenders may review:
- Lease length
- Ground rent provisions
- Service charge arrangements
- Repairing obligations
- Building insurance responsibilities
- Rights of access
- Commercial lease terms affecting the building
- Restrictions on letting
- Use clauses
- Maintenance obligations for shared areas
Short leases, unclear repairing obligations, or unusual building insurance arrangements can complicate the mortgage.
Rental Income and Stress Testing
Buy-to-let lenders usually assess whether the expected rent supports the mortgage payment under their affordability model. This is often known as an interest coverage ratio or rental stress test. A flat above commercial premises may offer a higher yield because the purchase price is lower than a similar flat in a purely residential block. However, a higher yield does not guarantee mortgage approval. The lender still needs to be comfortable with the property itself.
Borrower Profile
The lender will also assess the applicant. This can include:
- Credit profile
- Deposit source
- Landlord experience
- Income position
- Existing portfolio
- Personal or limited company structure
- Background properties
- Previous buy-to-let performance
- Whether the applicant is UK-based, expat, or foreign national
A strong borrower profile can help, but it does not override an unacceptable property type.
Deposit Requirements for Flats Above Commercial Premises
Deposit requirements vary by lender, property type, and borrower profile. In many cases, specialist or higher-risk properties may require a stronger deposit than a standard buy-to-let. As a guide, landlords should be prepared for the possibility of:
- Lower maximum loan-to-value
- More conservative valuation assumptions
- Higher pricing than mainstream BTL products
- A requirement for stronger rental cover
- More detailed underwriting
- A larger deposit if the valuer is cautious
The exact deposit depends on the case. A flat above a quiet office may have more options than a flat above a late-night takeaway. A property in a high-demand London location may be treated differently from a similar property in a weaker resale market.
Personal Name or Limited Company SPV?
Many landlords now consider buying through a limited company or SPV. This can be useful for tax planning and portfolio structuring, but it does not automatically make the property more acceptable to lenders. For an above commercial BTL mortgage, the lender still needs to approve:
- The property
- The commercial unit below
- The valuation
- The rental income
- The borrower or directors
- The company structure
- The deposit source
- The legal title and lease
An SPV can be suitable for experienced investors and portfolio landlords, but the structure should be reviewed alongside the property risk. If you are unsure whether to buy personally or through a limited company, Lockwell Finance can help you compare the mortgage routes and documentation requirements before you proceed.
When Bridging Finance May Be More Suitable
A standard buy-to-let mortgage may not be the right first step in every above commercial case. Bridging finance may be worth considering where:
- The property needs refurbishment before it can be let
- The flat is not currently mortgageable
- The lease needs extending
- The title or access issue needs resolving
- A fast auction completion is required
- The property has strong potential but does not yet fit standard BTL criteria
- You plan to improve the property before refinancing
- The commercial use below creates uncertainty that needs further review
For example, if you are buying a tired flat above a shop at auction and it needs works before letting, a refurbishment bridging loan may be more practical than trying to force a standard buy-to-let mortgage from day one. The key is the exit strategy. If the plan is to refinance onto a buy-to-let mortgage, the property must be likely to meet lender criteria once the works or legal issues are resolved.
If the property needs speed, works, or title clean-up before it fits a normal buy-to-let lender, speak to Lockwell Finance about a bridging-to-BTL strategy.
Practical Checklist Before Buying a Flat Above a Shop
Before you proceed with a flat above shop mortgage application, gather as much information as possible.
Property Details
- Full property address
- Property type and floor level
- Leasehold or freehold status
- Lease length
- Number of flats in the building
- Separate entrance details
- Access route
- Current condition
- Planned works
- Whether the flat is already tenanted
- Expected monthly rent
Commercial Unit Details
- Business type below
- Opening hours
- Whether food is prepared on site
- Extraction systems or vents
- Waste storage location
- Delivery arrangements
- Late-night activity
- Noise or odour concerns
- Current commercial lease terms if known
- Whether the unit could change use
Financial Details
- Purchase price or estimated value
- Required loan amount
- Deposit amount
- Deposit source
- Personal or company purchase
- Applicant income
- Existing properties
- Existing mortgages
- Target completion date
Legal and Compliance Details
- Lease restrictions on letting
- Building insurance arrangements
- Service charge structure
- Repairing responsibilities
- Fire safety information
- Gas and electrical safety evidence where applicable
- Planning or conversion history if the flat was previously commercial
- Any unusual title restrictions
The more information you provide at the start, the easier it is to approach the right lender and avoid unnecessary declines.
Common Reasons Applications Are Declined
The Commercial Use Is Too High Risk
A lender may reject the case if the property is above a takeaway, bar, nightclub, late-night off-licence, or another business considered too risky.
The Valuer Does Not Support the Property
Even where the lender is initially open to the case, the valuer may conclude that the commercial element affects resale demand or marketability too much.
Access Is Poor
If the residential access is through the shop, across a commercial yard, or via an insecure alleyway, the lender may be uncomfortable.
The Lease Is Not Lender-Friendly
Short leases, high ground rent, unclear repairing obligations, weak rights of access, or unusual insurance arrangements can cause problems.
Rental Income Does Not Fit the Stress Test
Even if the property is acceptable, the rent must usually support the mortgage under the lender’s calculation.
The Borrower Profile Is Too Complex
Adverse credit, unclear deposit source, limited landlord experience, overseas income, or a complex company structure may reduce lender options.
The Property Is Misclassified
Some buyers assume they need a buy-to-let mortgage when the property is actually semi-commercial. This can happen when they are buying the whole building rather than just the flat.
Case-Style Examples
Example 1: Flat Above a Pharmacy
A landlord wants to buy a leasehold flat above a pharmacy on a busy high street. The flat has its own entrance, the business operates normal daytime hours, and there are similar flats nearby with good rental demand. This may be acceptable to a wider range of specialist buy-to-let lenders, subject to valuation, lease details, and rental stress testing.
Example 2: Flat Above a Late-Night Takeaway
A landlord wants to buy a flat above a hot food takeaway. The business opens late, has extraction equipment, and stores commercial bins near the residential entrance. This may be harder to place. Some lenders may decline immediately, while others may only consider it with a conservative valuation, stronger deposit, and detailed review.
Example 3: Whole Building with Shop and Flats
An investor wants to buy a building with a shop downstairs and two flats above. The commercial unit and residential units are part of the same title. This may not be a standard above commercial BTL mortgage. A semi-commercial or mixed-use finance route may be needed.
Example 4: Auction Flat Above a Vacant Unit
A buyer wants to purchase a flat above a vacant commercial unit at auction. The flat needs refurbishment, and the use of the commercial unit is uncertain. A bridging finance route may be more realistic first, with a planned refinance once the works are complete and the commercial position is clearer.
How to Improve Your Chances of Approval
Get the Commercial Use Confirmed Early
Do not rely only on the estate agent’s description. Confirm the actual use of the commercial premises, opening hours, and any obvious nuisance risks.
Check Access Before Making an Offer
Separate, secure, and clearly residential access can strengthen the case.
Review the Lease Before Paying Too Much in Fees
Lease issues can derail otherwise workable cases. Ask your solicitor to check lease length, letting rights, repairing obligations, service charges, and insurance arrangements.
Use Realistic Rental Figures
Overstated rental income can cause problems later. Lenders may rely on the valuer’s rental assessment, not just the agent’s estimate.
Avoid Random Lender Applications
Multiple unsuitable applications can waste time and create unnecessary credit searches. Specialist placement matters for this type of property.
Prepare a Strong Pack
A clear pack should include property details, photos, rent estimate, commercial unit details, borrower profile, deposit evidence, and purchase structure.
Have a Backup Route
If standard buy-to-let lending is not possible immediately, bridging, refurbishment finance, or a semi-commercial route may still make the deal viable.
Is a Flat Above Commercial Premises a Good Buy-to-Let Investment?
It can be, but the numbers need to be assessed properly.
Potential Benefits
- Lower purchase price than similar flats in purely residential blocks
- Strong town-centre tenant demand
- Good transport and amenity access
- Potentially higher rental yield
- Less competition from cautious buyers
- Possible value-add opportunity if the property needs improvement
Potential Risks
- Fewer lenders
- Higher deposit requirement
- Valuation uncertainty
- Harder resale
- Tenant complaints about noise or smells
- Insurance complexity
- Fire safety considerations
- Commercial unit changing use
- Leasehold restrictions
- More due diligence required
The best opportunities are usually properties where the commercial risk is limited, the access is strong, the local rental market is proven, and the purchase price reflects the additional lending risk.
Investor Insight: The Discount Must Be Worth the Complexity
A common mistake is treating every flat above commercial premises as a bargain. A lower price does not automatically mean a better investment. The discount should compensate for:
- Reduced lender choice
- Potentially higher finance costs
- More valuation uncertainty
- Possible resale limitations
- Extra legal checks
- Longer mortgage process
- Greater tenant management risk
A good way to assess the deal is to compare it against a similar standard flat nearby. Ask:
- How much cheaper is this property?
- Is the yield meaningfully stronger?
- Will lender costs reduce the benefit?
- Could the flat be harder to sell later?
- Would tenants accept the commercial use below?
- Is the commercial unit likely to change use?
- Does the exit strategy still work if the valuation is lower than expected?
If the only advantage is a slightly lower purchase price, the risk may not be worth it. If the property has a strong yield, good tenant demand, acceptable commercial use, and a realistic finance route, it may be a worthwhile specialist investment.
What Lockwell Finance Can Help With
Lockwell Finance supports landlords and investors with property finance that fits the deal, not just the product name. For properties above commercial premises, we can help with:
- Buy-to-let mortgage options
- Specialist lender placement
- SPV limited company buy-to-let
- Portfolio landlord cases
- Bridging finance
- Refurbishment bridging
- Semi-commercial finance routes
- Refinance planning
- Deposit and documentation guidance
- Mortgage calculator and affordability review
- Clear next steps before application
Because this type of property is highly case dependent, early advice can save time, cost, and frustration. Send us the property address, purchase price, expected rent, commercial unit type, and your planned deposit. We will review the scenario and confirm the most realistic finance route.
FAQs
Can I get a buy-to-let mortgage for a flat above a shop?
Yes, it can be possible to get a buy-to-let mortgage for a flat above a shop, but it depends on the lender, the business below, the access, the lease, the rental income, and the valuer’s comments. A flat above a quiet retail shop is usually easier than a flat above a late-night takeaway or bar.
Is a flat above commercial premises harder to mortgage?
Yes, it can be harder to mortgage because lenders may see the property as higher risk. They will consider noise, smell, fire safety, resale demand, tenant appeal, access, and the type of commercial premises below.
Can I get a mortgage above a restaurant or takeaway?
It may be possible, but it is more difficult. Restaurants and takeaways can raise concerns about smells, extraction, fire risk, waste, deliveries, and late opening hours. Some lenders may decline these cases, while others may consider them subject to valuation and stronger overall criteria.
Do I need a commercial mortgage for a flat above a shop?
Not always. If you are buying only the residential flat, you may need a buy-to-let mortgage from a lender that accepts flats above commercial premises. If you are buying the whole building, including the shop and flat, you may need a semi-commercial or mixed-use mortgage.
Will the rent need to be higher for an above commercial BTL mortgage?
The rent must usually meet the lender’s buy-to-let affordability calculation. A higher yield can help, but it does not guarantee approval because the lender must also be comfortable with the property and commercial risk.
Can I buy a flat above commercial premises through a limited company?
Yes, many landlords buy through an SPV limited company, but the property still needs to meet lender criteria. The lender will assess the flat, commercial unit, rental income, company structure, directors, and deposit source.
